mRNA-4157 (Intismeran autogene) is not a generalized product you pull off a shelf. It is an algorithmic manufacturing pipeline. Moderna and Merck ingest raw, unstructured local data (a patient’s tumor sample), run it through a massively parallel sequencing workflow, and output a customized synthetic mRNA sequence that encodes up to 34 unique neoantigens.
Think of it like this: mRNA-4157 is to oncology what Palantir Foundry is to enterprise software. ChatGPT and Claude are generalized, one-to-many foundational models. Palantir Foundry ingests chaotic, siloed enterprise data and builds a bespoke operational ontology mapping the unique “mutational signature” of a single company. Both platforms operate on the exact same philosophical framework: infrastructure designed for extreme, 1-to-1 mass customization.
This isn’t theoretical. The FDA is literally demanding that Moderna’s machine learning algorithm be submitted alongside the biologic data as part of the regulatory package. The government is treating the software as the drug. You cannot replicate this with off-the-shelf code.
2. Escaping the Blockbuster Patent Trap:
Standard drugs eventually expire and lose their patent exclusivity. Merck’s crown jewel, Keytruda, is essentially the CrowdStrike Falcon of oncology—an incredibly valuable, standard-issue defensive tool. But Keytruda is marching toward a massive patent cliff and facing legitimate, structural competition from Summit Therapeutics.
This is why mRNA-4157 is a massive paradigm shift. Because it is an individualized pipeline, it fundamentally breaks the traditional patent expiration trap. The moat isn’t just a chemical structure; it is the proprietary sequencing algorithm, turnaround speed, and the hundreds of millions Moderna spent building its internal physical manufacturing and software infrastructure. You cannot genericize a bespoke, closed-loop supply chain.
3. BioNTech’s Validation, Moderna’s Execution:
This moment completely validates BioNTech’s foundational thesis, but in biotech, first-mover advantage is everything. BioNTech pioneered the individualized neoantigen concept, but they played it safe. They de-risked their flagship candidate (BNT122) by entering into a deep partnership with Genentech/Roche. By offloading the R&D cost, they ceded absolute control, slowed their timeline, and hard-capped their revenue ceiling.
BioNTech is still grinding through Phase 2 trials for pancreatic and colorectal cancers. Moderna took a highly concentrated approach, absorbed the raw risk, executed faster, and pushed Phase 3 across the finish line years ahead of their rival. In a winner-take-all infrastructure race, BioNTech’s conservative strategy is making them look a distant second-place finisher.
4. The Value is Locked in the IP Trench Warfare:
Do not ignore the legal reality: the absolute value of Moderna and mRNA-4157 is locked in a vicious patent war over the underlying Lipid Nanoparticle (LNP) delivery tech. This is why Moderna pays one of the top legal executives in the pharmaceutical and biotechnology industries, Shannon Thyme Klinger, as their Chief Legal Officer. She is a ruthless, tier-one legal tactician, and her job is to defend the fortress.
Earlier this year, Moderna dropped a staggering $2.25 billion to settle a massive LNP patent dispute with Genevant and Arbutus. Why pay that much? Because controlling the platform IP means controlling the toll bridge for the entire next generation of mRNA therapeutics. Moderna is fighting Pfizer, BioNTech, and Alnylam in a global trench war because if you own the LNP patents, you tax the entire future of the industry. This litigation will dictate who actually captures the long-term margin.
5. The Behavioral Economics of Adoption (Healthy vs. Sick):
We have to separate the underlying mRNA technology from the political baggage of the pandemic. Infectious disease vaccines are inherently a tough sell because you are asking a perfectly healthy person to take a drug that will likely make them feel sick to prevent a statistical probability. It is a breeding ground for political friction.
Oncology completely flips the behavioral economics. You aren’t dealing with a healthy populace; you are dealing with a patient who has had a tumor excised and is staring down the barrel of a lethal relapse. When an individualized therapy can reduce the risk of cancer recurrence by 30 to 50 percent, the calculus is absolute zero: why wouldn’t you take that? The choice isn’t between feeling fine and mildly ill. The choice is between an experimental lifeline and a painful death. This eliminates the political friction and shifts the adoption curve entirely from push to pull.
6. The Peak Revenue Fallacy (The Hunger Games):
Wall Street analysts pricing this asset solely on its “peak adjuvant melanoma sales” are committing financial malpractice. This isn’t just about melanoma. The late-stage data is a proof-of-concept that creates an entirely new therapeutic space for solid tumors. Moderna survived a bloody, decade-long biotech Hunger Games and walked out with the prize.
Retail investors locking in their gains today are going to brutally regret it. If this paradigm shift were a baseball game, we are still in the warm-ups. Would you buy a front-row ticket to the World Series and leave the stadium before the first pitch is even thrown? Selling this news because of near-term scaling costs is missing the forest for the trees. This is a foundational shift in how we treat human disease, and the compounding returns have not even started.
“The IT department of every company is going to be the HR department of AI agents in the future. Those digital employees are going to work with our biological ones, and that’s going to be the shape of our company in the future.” — Jensen Huang, CEO of NVIDIA (CES 2026)
If the Godfather of AI is right, the future of work isn’t just better video calls—it’s managing a hybrid human + digital workforce. While the market wrote Zoom off years ago, the company has quietly repositioned itself as the natural “HR Department” for those agents.
Investors are still psychologically scarred. Mention Zoom and the ticker probably triggers 2021 PTSD. Just the mention of the ticker probably feels like a personal attack. Even Cathie Wood fully liquidated her position in late 2023, but what if her investing thesis was correct, just early? While the market is staring in the rear-view mirror, they are missing a fortress balance sheet and a hidden AI stake that could soon rival the company’s entire current valuation.
The Cash Fortress (The Valuation Floor)
Forget the hype. Let’s look at the math. This is where the margin of safety lives:
You are buying a premium SaaS platform—a global brand with 140k+ enterprise seats and sticky workflows—at ~7.5x FCF. For context, boring hardware companies and legacy retailers trade at higher multiples. The market is pricing Zoom for a slow death, but the cash flow says it’s thriving.
This is the definition of “Dirt Cheap.” Even without a major catalyst, the downside is protected by a mountain of cash and a business that produces liquidity.
The Anthropic Windfall: A “free” Home Run
In 2023, Zoom quietly invested $51 million in Anthropic at a $4 billion valuation. Fast forward to February 12, 2026: Anthropic closed a $30 billion Series G at a $380 billion post-money valuation.
Analysts peg Zoom’s stake at $2.5–$4.5 billion today. If Anthropic IPOs at the rumored $750B+ range this year:
The Math: Zoom’s stake could hit $10 billion+.
The Proxy Play: Amazon owns more of Anthropic, but because AMZN is a $2.5T behemoth, the stake only moves their needle 3-5%.
The Impact: For a giant like Amazon, that’s a rounding error. For Zoom, it’s nearly 50% of its current market cap. When you buy Zoom today, you aren’t just buying a software company; you’re buying a massive, liquid stake in the leading “reasoning” AI- for almost nothing.
The Gen Z Factor & The “War Chest”
As Gen Z enters the C-suite, the “Microsoft-only” era is fading. 2026 data show that Gen Z and Millennials (who now make up over 60% of the workforce) prefer the low-friction and video-first nature of Zoom. They want a “System of Action,” not a “System of Record.”
The Competitive Advantage (vs. Salesforce/CRM): CRM is a giant, but it has virtually no cash compared to Zoom’s hoard. Zoom is lean, founder-led, and has a $7.8B war chest to acquire high-growth AI startups to force that return to 15% revenue growth.
The “Anti-Microsoft” Pivot: The Orchestrator of AI
The bear case is simple: “Microsoft Teams is free, so Zoom is dead.” But the data shows a “David vs. Goliath” moment is happening in the Enterprise:
Enterprise Revenue: Grew 7.1% last year (Q4 FY26), triple the rate of the small-biz segment.
The Fortune 10 Win: Zoom recently displaced Cisco in a 140,000-seat deal. Why? Because giants are tired of “Microsoft Lock-in.
The Federated AI Approach: While Microsoft locks you into OpenAI, Zoom’s AI Companion 3.0 is a “conductor.” It switches between Anthropic (Claude), OpenAI (GPT-5), and its own Small Language Models in 0.1 seconds. It’s “Best-of-Breed” vs. “Whatever Microsoft bundles.”
Metric
Salesforce (CRM)
Zoom (ZM)
Why This Favors Zoom
Market Cap
~$179.7B
~$25.3B
Lower Bar: Easier for a $25B company to 2x than a $180B giant.
Net Cash
$8.4B
$7.8B
Acquisition Firepower: Zoom’s cash is 30% of its market cap. CRM’s is only ~4%.
Enterprise Seats
~150,000 Companies
~220,000 Companies
Upsell Runway: Zoom has more “doors” to walk through to sell Phone/AI/Contact Center.
AI/Agent Displacement
High Risk
Lower Risk
Salesforce relies on “human” seats (Sales/Support). Zoom’s video/phone is “infrastructure.”
Debt Load
$7.6B
$0
Flexibility: Zoom has zero “interest rate heartburn.”
Why Zoom Wins the “Agent” War Yuan Saw First
While Salesforce’s Marc Benioff spent 2025 screaming about “Agentforce,” Eric Yuan was already there in June 2024. In his Decoder podcast interview nearly two years ago, Yuan laid out a “prophetic” vision of “Digital Twins.” He envisioned AI agents that don’t just summarize meetings but attend them for you, negotiate contracts on your behalf, and make decisions based on your specific “First Principles.”
At the time, the market laughed it off as sci-fi. Today, it is the north star for the entire industry. Zoom wins here because:
The System of Action: AI agents don’t want to navigate 20 layers of a legacy CRM. They want to “join the meeting,” take notes, and execute tasks. Zoom is where the work actually happens.
The Switzerland of Tech: Zoom doesn’t force you into one LLM. Your digital twin can pick the best engine without vendor lock-in.
Zoom Phone just crossed 10 million paid seats. It’s the “wedge” that’s breaking open massive platform deals.
Rare Asymmetry with Minimal Capital Risk
This is a very clean, asymmetrical setup in tech. Zoom doesn’t need Microsoft or Salesforce to implode. It doesn’t need another pandemic. It just needs a founder-led company with a history of delivering during uncertain times to keep executing and achieving a very attainable 10-15% growth rate. Even a 20-30% growth, though wishful, is not delusional.
The Risks? This thesis will be tested. The primary risk here isn’t the total loss of capital—at 7.5x FCF, the floor is remarkably solid. Instead, the risk is opportunity cost. We don’t know how long it will take for the market to wake up and re-rate this “pandemic relic” into a “2026 AI powerhouse.”
In my view, the risk of losing principal is surprisingly low, but the patience required to see the thesis materialize is high.
Disclosure: I am not bearish on Microsoft; in fact, I own shares in MSFT. I am not bearish on CRM (Salesforce), though I currently own no shares. I simply believe Zoom is a mispriced anomaly hiding in plain sight.
This is exactly why the average retail investor consistently underperforms the S&P 500: they are biologically wired to buy high and sell low.
We are currently witnessing a classic “Retail Doom Loop” with Duolingo (DUOL). If you’re staring at the price ticker instead of the fundamentals, you’ve already lost the game.
Your Biology Is Your Worst Enemy
The “lizard brain” (the amygdala) is a marvel of evolution designed to keep you alive, not to make you wealthy.
If your tribe started running 50,000 years ago, you didn’t pause to ask, “Is that a lion or just a technical correction?” You ran. In the wild, that is survival. In the markets, that is financial self-destruction.
The Tribal Sell: The stock drops 20% in a week → your lizard brain screams, “The tribe is fleeing! There must be a predator (AI) I can’t see!”
The Narrative Pivot: Loss aversion (we feel the sting of losses roughly 2x more than the joy of gains) forces us to rewrite history. We don’t say “the price is lower.” We say “the company is failing.” It’s emotional pain relief dressed up as “analysis.”
The Retail Loop of Doom
Retail investors rarely buy value; they buy social proof. Here is how the loop destroys portfolios:
The Validation Phase: Retail ignores the stock while it’s quietly forming a base. They only jump in after a +40% rally because “the price action proves it’s good.”
Conviction Evaporation: Because the thesis was built on a green line moving up and not fundamentals, the very first red candle triggers panic.
The Narrative Flip:
Price Up: “Luis von Ahn is a genius; the owl is the future of AI.”
Price Down: “The app is a fad; AI is disrupting them; the CEO is distracted.”
This is reflexivity at its most toxic: price shapes mood, mood shapes selling, and selling drives the price lower until the entire tribe has fled the cave.
Prisoners of the Moment
The current wave of hate toward Duolingo isn’t analysis—it’s emotional venting from people who bought near the $500+ peak in May 2025 and are now feeling the burn. They are prisoners of their own portfolio pain, not the reality of the business.
If you’re “hating” the company today, ask yourself: Were you investing, or were you gambling with leverage and money you couldn’t afford to lose? Your anger isn’t with the green owl. It’s with your own risk management.
The Irrelevance of Anchoring
“I bought at $500, so I need it to get back there to be ‘right.’”
Your entry price is 100% irrelevant. The past transaction cannot be undone. All that matters is what the business is worth today versus its future potential. If you overpaid for a great house in a bidding war, the house didn’t suddenly become “bad”—you just paid a premium for a premium asset.
The market is currently offering Duolingo shares at a 70–80% discount to the peak. I’m betting this is normal growing pains, not an irreparable decline. No great company avoids “off years.”
I very much could be wrong but my cost basis and holding period is unique to me. I am comfortable with the risk, and that’s all that matters.
Pivot from Strength: The Agility Advantage
Ignore the stock price for a minute. Duolingo is acting from a position of extreme strength. Compared to the “supertankers” of digital media, Duolingo is a nimble speedboat.
Company
Market Cap
Employees
The “Agility” Factor
Duolingo
~$4.7B
~850
Speedboat: Can pivot the entire roadmap in a month.
Spotify
~$106B
~7,300
Tanker: Massive scale, but harder to maneuver.
Netflix
~$406B
~16,000
Supertanker: Incredible reach, but heavy overhead.
From first principles, it is infinitely easier for Duolingo to pivot its roadmap to AI-native learning than for these behemoths to turn their ships. Focusing on user growth over immediate monetization is the correct long-term move, even if it causes short-term “earnings heartburn.”
Planting vs. Harvesting
Wall Street is throwing a tantrum because Duolingo is “foregoing” more than $50 million in bookings to remove ad friction.
The contrarian view? They aren’t losing money: they’re reinvesting in distribution. They are betting that a network effect of 100 million daily active users (DAUs) will be worth far more than squeezing a few extra bucks out of frustrated free users today. They are trading short-term harvesting for long-term dominance.
The AI “Barrier to Success”
In a world where everyone has GPT-4, the winner isn’t the one with the “best” AI, it’s the one with distribution, brand, and proprietary data. Duolingo has billions of data points on how humans learn and a owl brand that is a global cultural icon. They aren’t being disrupted; they are the disruptors. They are using their $1.04 billion cash pile and a new $400 million buyback to repurchase shares while the lizard-brain crowd hands them over at a massive discount.
Final Thoughts:
I’ll concede this: if you signed up for a quiet, slow-and-steady compounder, DUOL isn’t for you. Luis von Ahn is in “Full Founder Mode,” and that makes some shareholders uncomfortable.
But if you have an appetite for volatility and believe in the long game, this is a prime investment candidate for a Roth IRA. The potential gains are astronomical—and entirely tax-free.
Stop confusing a high-volatility stock with a risky company. They are not the same thing. If they hit 100M DAUs by 2028, buying DUOL near a $4.7B valuation today will look a lot like buying Netflix in 2011. Forget your entry price and the stock price. Focus on the compounder.
Most investors are still fixated on the smoking crater of the 2022 bubble. They haven’t refreshed their mental models to reflect Lemonade’s evolution from a cash-burning startup to a data-driven compounding machine. That lingering skepticism? It’s pure alpha.
The Pivot to Profitability
Lemonade has long been a tantalizing story, but the big “if” was always profitability. Now we’re witnessing the “how.” The narrative has flipped from raw growth to ruthless operational efficiency. Key highlights from Q3 2025:
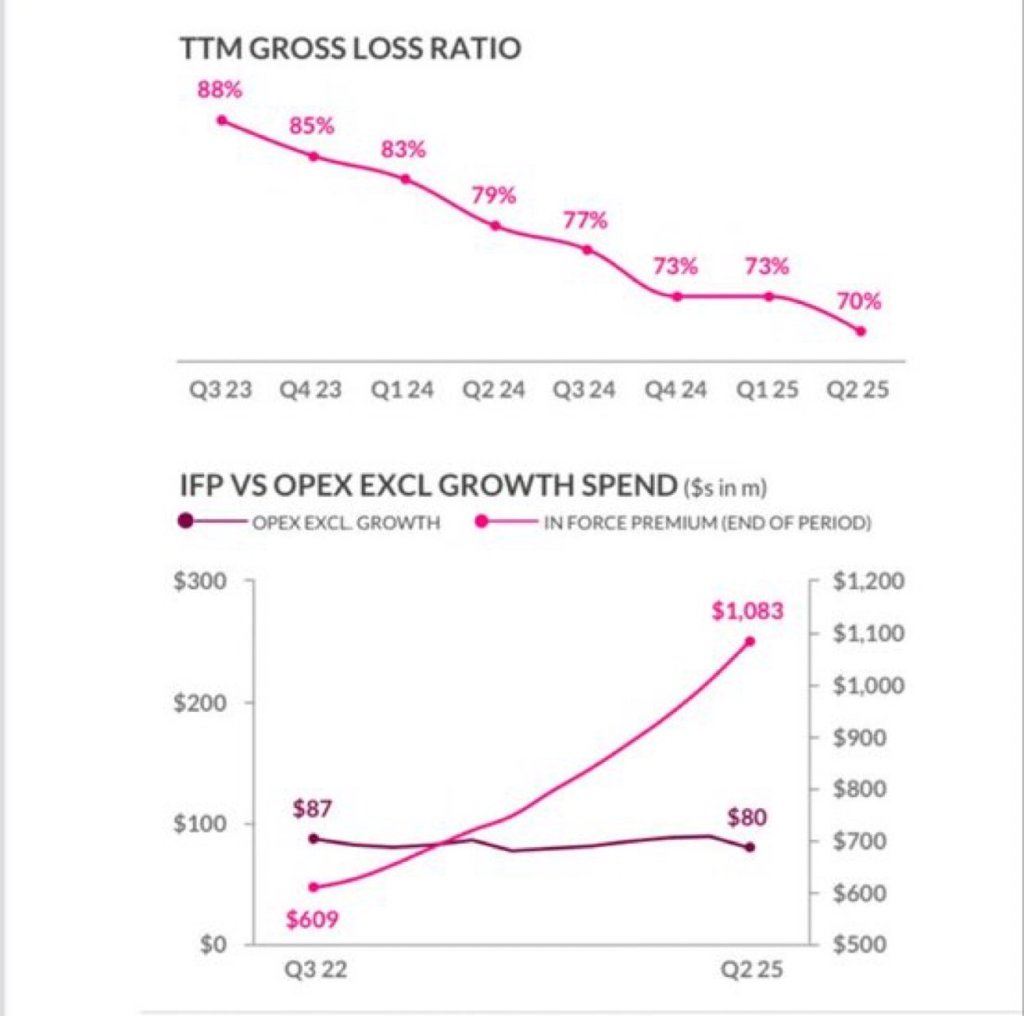
In-Force Premium (IFP): Reached $1.16 billion, up 30% YoY—their 8th straight quarter of accelerating growth.
Loss Ratio Mastery: Gross loss ratios have plummeted from 73% down to 62%. In insurance, that 11-point swing is the difference between a straw house and a fortress.
Efficiency at Scale: Loss Adjustment Expense (LAE) ratio—the cost to process claims—dropped to 7%, below legacy players like Progressive or Geico (typically 9-10%).
Reinsurance Revolution: Primary quota share ceded fell from 55% to 20%. Lemonade’s finally retaining the “juice” instead of outsourcing most profits to reinsurers.
The Coiled Spring: The Tesla Shot of Adrenalin
A coiled spring demands a spark. Enter the Autonomous Car Insurance launch: Arizona on January 26, 2026, and Oregon in February. By plugging directly into Tesla’s Fleet API, Lemonade delivers ~50% per-mile discounts with Full Self-Driving (FSD). This isn’t just insurance; it becomes a viral customer magnet.
The “X” Factor: Tesla influencers’ publicity and Elon Musk’s orbit have generated millions of organic impressions. In a world where a Super Bowl ad costs $7 million for 30 seconds, Lemonade effectively ran a “digital Super Bowl campaign” for free.
The Safety Edge: Lemonade’s data shows FSD-assisted driving is roughly 2x safer than human driving. They are pricing risk with high-resolution telemetry that traditional insurers simply can’t touch.
The 10x Revenue Multiplier
The hidden gem? Premium per Customer is now $403 (up 5% YoY). As the “Lemonade generation” matures from $15/month renters to $150/month car/pet/home bundles, revenue per user could 10x while acquisition costs hold steady. It’s the flywheel legacy insurers envy.
The Bottom Line
I am extremely bullish. This isn’t the same as buying the hype at 70 in 2020. Over 5 years later, the company is dramatically more efficient, and “Car” is a proven engine rather than a theoretical startup.
The Lemonade thesis was never about a sleeker app; it was about a fundamentally superior information architecture. While the legacy giants like State Farm or Geico price based on broad ‘buckets,’ Lemonade is finally proving it can price at the individual level.
With the stock retracing under 70 (currently hovering around $63–$64 after a volatile start to the year), we may be in the final throes of disbelief. Q4 2025 Earnings Call on Feb 19th is just days away. The data is trending toward a triple-threat: accelerating growth, massive margin expansion, and a clear path to profitability. With the recent winter storms being less catastrophic than feared, the pathway for Lemonade to run in 2026 and 2027 is wide open.
Aritzia’s Q3 FY2026 was one of its best quarters ever—like a walk-off home run in the playoffs. For the first time in the company’s history, they crossed the CAD 1 billion revenue mark in a single quarter, hitting CAD 1.04 billion, up 42.8% YoY.
Aritzia grew sales by nearly 43% while increasing inventory by only 10%. This means their inventory turnover is accelerating and they’re selling clothes almost as fast as they can get them off the trucks. This leads to fewer markdowns and higher full-price selling, which is exactly why their gross profit margin expanded by 30 basis points to 46% this quarter. This 4.3x “Sales-to-Inventory” growth ratio suggests an operational efficiency that makes even the “Mag Seven” look sluggish.
Compare that to Lululemon: Their inventory grew by 11%, but revenue only grew by 7%. When inventory outpaces sales, it usually leads to one thing: markdowns. In fact, Lululemon’s Q3 earnings call explicitly noted that gross margins were squeezed by higher markdowns (up 90 basis points) and tariff impacts. They have ~$2 billion in yoga pants and gear sitting in warehouses that they’re struggling to move at full price.
Aritzia is actually running a more efficient operation relative to its growth than even Nvidia right now. Here’s a quick side-by-side:
Company
Sales Growth (YoY)
Inventory Growth (YoY)
Ratio (Sales/Inventory Growth)
Aritzia
42.8%
10%
~4.3x
Nvidia
62%
~32% (9M cumulative)
~1.9x
Lululemon
7%
11%
<1x
Aritzia’s ability to scale this aggressively while staying so disciplined on inventory is retail execution at its finest, turning hype into real, high-margin momentum. If you’re looking at consumer discretionary winners in this environment, Aritzia is flexing harder than most realize.
This quarter also saw the late-October launch of the Aritzia Mobile App, which hit 1.4 million downloads and became the #1 shopping app in North America on day one. E-commerce revenue surged 58.2%, proving that “Everyday Luxury” translates perfectly to a high-frequency digital experience.
In 2027, Aritzia isn’t just signing a lease; they’re opening a new 40,000 square foot flagship store of the former Nordstrom footprint in Vancouver’s CF Pacific Centre. Aritzia is officially planting its flag on the grave of the defeated old guard.
This is the coronation of a new king. It marks the definitive shift from the bloated, “everything-for-everyone” department store model to a new, aggressive power dynamic. Aritzia has engineered a psychological moat known as “Everyday Luxury.” This isn’t just fashion; it’s a socioeconomic pivot that captures the soul of the modern consumer:
High-End Design: The clothes look like they belong on a Paris runway (minimalist, high-quality fabrics, tailored fits).
Attainable Pricing: Because they control the supply chain, they can sell that “look” for $150–$400 instead of $2,000. By pricing themselves 30–40% below heritage luxury (The Row, Celine) but 20–30% above fast fashion (Zara, H&M), they’ve created a “sweet spot” of attainable exclusivity.
The Result: They’ve captured the “HENRY” (High Earner, Not Rich Yet) demographic. This group is remarkably resilient to macro downturns because they view Aritzia as a “reasonable” yet “necessary” indulgence rather than an extravagant splurge.
The Psychology: Since “big” milestones (real estate, stable pensions) are increasingly out of reach for many, the HENRY demographic is reallocating their discretionary cash into “micro-luxuries” that provide immediate status and emotional ROI.
As we are witnessing with Saks, the “department store” represents the old middle class: a place where you go to see a little bit of everything. It’s a dying generalist model in a world that’s increasingly specialized.
The Old Way: Middle class = Access to variety.
The New Way: Middle class = Access to a vibe. Aritzia doesn’t just sell clothes; it sells a lifestyle aesthetic. When you walk into their “Super Flagships,” you aren’t shopping; you’re participating in a brand-curated experience.
The stock is trading at record highs with a P/E that reflects “perfection.” But Aritzia is just hitting its stride. They’ve successfully moved beyond “leggings and hoodies” into a full-wardrobe solution. It isn’t just superb execution by management; it’s capturing the vibe of today’s consumer.
I bought the stock as a small position in 2023 and have held it and will continue to hold it. If we’re using a baseball analogy, we are still very early. For Aritzia’s growth, we haven’t even entered the 7th inning stretch. Aritzia currently has roughly 72 boutiques in the US (out of 139 total). For context, Lululemon has about 374 stores in the US. Aritzia’s stated goal is ~150 boutiques total by 2027, with long-term potential for 180- 200+ overall, focusing heavily on US expansion (8-10 new boutiques annually, mostly in the US). If Aritzia hits its 150-store near-term target, revenue will likely triple as brand awareness hits a tipping point.
I am officially pegging Aritzia as a stock to buy during a market correction or pullback. Unlike legacy retailers, Aritzia is currently expanding its US footprint into a demographic that views “Everyday Luxury” as a non-negotiable part of their personal identity. This psychological moat, combined with an operational efficiency that is scaling faster than its infrastructure costs, makes Aritzia uniquely qualified to weather consumer weakness better than almost any peer in the sector.
If the market gives me a discount on this level of execution, I’ll take it.
Revolve Group (NYSE: RVLV) is the forgotten champion of apparel retail. While Wall Street obsesses over hyper-growth names and retail investors chase the next meme stock, Revolve quietly operates one of the strongest, most defensible business models in the entire consumer sector. It’s dismissed as “just another overpriced clothing seller,” but that superficial take misses two genuine superpowers that are extraordinarily rare in the apparel sector. This unique combination creates a company that is antifragile in a brutal, cyclical, low-margin industry, a combination that deserves far more attention than it gets.
Superpower #1: A Pristine, Fortress-Like Balance Sheet
Revolve has more cash and cash equivalents than total liabilities. This isn’t total assets minus liabilities. This is cash-on-hand exceeding all debt. As of September 30, 2025, Revolve held $315 million in cash, with total liabilities of just $226, leaving it net cash positive by nearly $90 million. (Revolve Group Announces Third Quarter 2025 Financial Results, 2025) In an industry notorious for leverage-fueled boom-and-bust cycles, this is almost unheard of. Look at Revolve’s closest competitors and legacy apparel names:
The RealReal → Negative net cash, drowning in $500+ million of debt
Victoria’s Secret → $4 billion in long-term debt, with cash covering only a fraction.
Guess? → Leveraged with debt-to-equity over 2x
Macy’s, Kohl’s, Abercrombie in their prior incarnations → Perpetual debt refinancings amid endless store closures
Most apparel retailers use leverage as oxygen. Revolve doesn’t need it. Zero net debt (actually net cash) gives them a massive margin of safety that investors in this sector are simply not accustomed to. In a downturn, Revolve can keep the lights on indefinitely without ever visiting a bank. In an upturn, they can aggressively buy back stock (they’ve already repurchased over 20% of shares outstanding since their 2019 IPO, including $100 million authorized in 2023), or acquire distressed brands/competitors for pennies on the dollar. Having such a fortress balance sheet creates real optionality.
Superpower #2: Consistently Elite Gross Margins (54% and Climbing)
The average apparel retailer scrapes by with gross margins of 30-50%. Revolve delivered a 54.6% gross margin in Q3 2025 (up 350 basis points YoY) and has maintained a 50-55% gross margin range for years. For context:
Louis Vuitton (LVMH) → 66%
Lululemon → 59%
Zara → 55-57%
Most everyone else → 30-45%
Revolve is operating at the same rarefied level as the very best branded apparel players on earth, despite being a pure-play online retailer without a physical-store crutch. Why does this matter so much? Because elite margins are Revolve’s ultimate defense against Amazon. Retail investors see “expensive clothes” and assume the model is fragile. In reality, those premium prices are the moat. Millennials and Gen Z raised on Instagram and TikTok aren’t shopping for the cheapest white t-shirt: they’re buying an identity, or an outfit that photographs well at Coachella. Revolve sells social currency. Customers happily pay 2–3 times more for the outfit that might cost less elsewhere because they’re paying for curation, discovery, and status. That willingness to pay a premium is exactly what produces 54%+ gross margins and sustains an average order value of $306 in Q3 2025 (up 1% YoY).
And those margins are what keep Amazon at bay. Amazon dominates commodity fashion: fast, cheap, endless selection. If Revolve ever tried to compete on price, Amazon would crush them with its scale and logistics. But Revolve isn’t playing that game. They’re playing the art of the brand premium game, something Amazon isn’t going to win. Even after 25+ years and billions invested, Amazon has failed to crack premium or luxury fashion in any meaningful way, with a fashion gross margin hovering around 20-30%, far below the industry standard. Jeff Bezos himself has admitted that building a real fashion brand is one of the few things Amazon hasn’t figured out.
The Rare Combination
Put the two superpowers together, and you get something compelling:
A net-cash balance sheet → survives any storm, buys back stock aggressively, and is opportunistic with M&A.
54%+ gross margins → funds growth, defends against Amazon, produces torrents of free cash flow (up $265% YoY to $59 million in the first nine months of 2025.
This defensive balance sheet and offensive margin profile is the definition of antifragile in retail.
Revolve is clearly doing something different: one that builds on digital and social infrastructure to erect a curation and brand moat. They sell the Revolve experience, which allows them to charge premium, full-price prices (high Average Order Value). Using first principles, Revolve’s main product isn’t a dress; it’s the marketing expense. The influencer trip is not just a cost; it is the intangible asset that allows them to maintain a $300 price point for a dress. This experiential luxury marketing, powered by a network of 5,000+ influencers, has driven its owned-brand penetration to 35% of sales, further boosting margins.
The focus on experiential luxury marketing allows Revolve to build a digital model while using temporary pop-ups as low-CapEx market research before committing to a permanent location. Their Aspen pop-up in December 2024 converted to a full flagship in June 2025 after crushing performance metrics, and they’re replicating the playbook with a permanent store at LA’s The Grove. Focusing on brand experience, margins, and building a cash fortress creates optionality, which is a much different playbook than most apparel retailers play: heavy CapEx expansion to drive growth, which is more inflexible and likely requires leverage.
Very few companies in any industry possess both traits simultaneously. When you find one, especially one trading at a reasonable earnings multiple with a proven ability to grow, it’s worth paying attention. Revolve isn’t a “hot” stock. It doesn’t have 150% YoY growth. It is a quiet, compounding machine built on genuine structural advantages, like a pristine balance sheet and 54% margins that the market keeps overlooking.
Investing in the U.S. healthcare sector is akin to navigating a battlefield shrouded in fog. Stocks like UnitedHealth (UNH), Oscar Health, Progyny, Hims & Hers Health, or even Novo Nordisk may seem appealing, but a minefield of uncertainties surrounds them. I am skeptical whether UNH is the obvious value play.
Picture this: Deploying your capital is like sending troops into hostile, unpredictable terrain. If you’ve ever tangled with the American healthcare system, you know it’s a chaotic web of shifting regulations, bureaucratic red tape, and outright irrationality that can derail even the savviest investor’s plans.
UNH: A Distraction in the Fog
UnitedHealth is currently under a microscope, with the Department of Justice launching both civil and criminal investigations into potential fraud in its Medicare billing practices. These investigations, which are focused on allegations of overcharging and improper billing, could have significant financial and reputational implications for the company. For a long-term investor, this is a massive distraction. Regulatory scrutiny doesn’t just threaten your investment—it demands your time and energy, which are better spent hunting for truly innovative opportunities.
Is the broader healthcare sector undervalued? Signs suggest yes. But “undervalued” alone doesn’t justify making UNH a core holding. Short-term catalysts for a rebound are scarce. Unlike tech companies that can pivot swiftly, UNH is mired in a labyrinth of state and federal oversight, slowing progress to a crawl. This screams low-risk, low-reward: Park your money here, and you might watch it stagnate as inflation erodes your purchasing power.
The Opportunity Cost Trap
The real danger isn’t just losses—it’s opportunity cost, the silent killer that drains your portfolio’s potential. Opportunity cost is the potential benefit that is foregone when one alternative is chosen over another. Consider investors who snapped up ‘bargain’ Boeing shares during the pandemic. Sure, Boeing was cheap, with bankruptcy risks cushioned by its ‘too big to fail’ status and a near-duopoly in aviation. A Boeing bull might argue: ‘I’m up 30-50% over five years—what’s the problem?’ Two issues stand out:
That 30-50% lags the S&P 500’s 90-100% surge over the same period. Why take single-stock risk for returns that trail a broad index with far less stress?
Tying up capital in Boeing meant missing rockets like Nvidia’s jaw-dropping 1,500%+ run or the stellar gains from Palantir and MicroStrategy.
Piling into UnitedHealth feels like queuing for hours at a hyped-up New York City pizza joint for a $60 pie. Sure, it’s tasty, but was it worth skipping faster, cheaper (and equally delicious) options that don’t hijack your entire day?
I understand the appeal of this sector, having invested in healthcare stocks myself. But is now the right time to go all-in on UNH? I recommend a more cautious approach. In a market where value is hard to find, it’s important not to rush into a potential minefield just because it seems cheap. Patience and a keen awareness of opportunity cost can be your most powerful tools. Instead of making a significant investment in UNH, consider waiting for clearer signals where valuations don’t come with a heavy burden.
Philadelphia Phillies starting pitcher Zack Wheeler
As an investor, I’ve had a love-hate relationship with Lemonade stock. I loaded up too heavily right after its 2020 IPO, only to regret not buying more aggressively when shares dipped into single digits. If you’re considering this name, approach it with caution—it’s a classic high-risk, high-reward bet. Lemonade remains a young company in its growth phase, far from maturity.
In hindsight, the stock’s wild ride in 2021 was fueled by meme-stock mania. It skyrocketed to $188.30 on January 12, 2021, despite the company having under one million policyholders and no auto insurance offering at the time. That bubble burst spectacularly, but beneath the surface, Lemonade’s fundamentals are showing real signs of improvement.
Back to the Drawing board:
The company has always excelled in technology, innovation, and customer acquisition. Profitability, however, has been its Achilles’ heel. I’d liken Lemonade to a highly touted high school baseball pitcher: a laser fastball and a nasty arsenal of pitches, but zero command on the mound. Without control, even the most talented arm flames out quickly; a great repertoire of pitches means nothing if you don’t know where the ball is going.
For a while, its business model reflected this wildness: impressive growth and customer attraction (the 103-mph fastball and filthy slider) were negated by sloppy underwriting (walks and hit-by-pitches). Critics often hammered the company’s high loss ratio as an unsustainable business model.
Think of Lemonade as a young Roy Halladay or Zack Greinke. Both were first-round draft picks who bombed early in their MLB careers, getting demoted to the minors amid mechanical issues and poor results. But they adapted, refined their approach, and emerged as Hall of Famers. Lemonade is on a similar trajectory.
Rebuilding the mechanics
The data over the most recent quarters tells a story of Lemonade tackling its core risks head-on:
Loss ratios are improving dramatically, signaling better risk management and a tighter command of its underwriting.
It has slashed its quota-share reinsurance from ~55% to ~20%, meaning it now keeps more of the premium (and risk) in-house.
After pulling back on its auto insurance rollout, underwriting discipline has strengthened, setting the stage for renewed expansion.
At its core, Lemonade’s business isn’t as complicated as it seems. It’s exceptional at drawing in new customers through its AI-driven, user-friendly platform. If it can continue tightening risk controls, revenue growth should accelerate while losses/expenses stabilize.
The Bull Case Ahead
Wall Street is sleeping on the roadmap ahead. I expect Lemonade to rev up its auto insurance product, expanding beyond the current nine states. New offerings like phone or travel insurance could further juice growth, pulling more users into the ecosystem and unlocking bundling discounts for multi-policy holders.
I’m not hyping this as a sure thing, but my optimism feels more grounded now: rooted in a business that appears primed for scalable profitability. That said, risks abound: Lemonade lacks a deep moat against competitors or economic headwinds, and plenty could still derail it, much like a pitcher blowing out their elbow on a single throw.
Analysts will likely pile in late, chasing momentum rather than leading the charge. I could be wrong, falling into the retail investor trap of being too early or clinging to a thesis that fizzles. Uncertainties remain, but Lemonade looks increasingly deserving of a small portfolio allocation. The bull case could spark explosive upside volatility, especially as AI evolves from infrastructure plays (like Nvidia or Google) to application-layer disruptors. Lemonade’s AI-powered insurance model positions it to capitalize on this shift, potentially delivering venture-like returns in the years ahead. While it’s no Palantir clone, the ride ahead could be like an epic roller coaster.
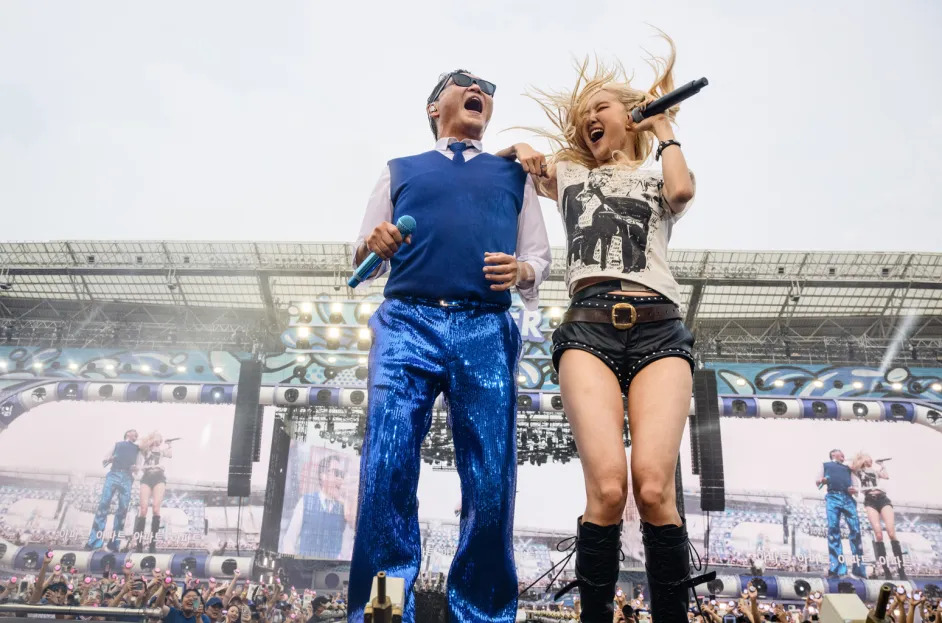
Palantir redefined data analytics, while Gangnam Style redefined K-pop. Both achieved unexpected success through unconventional approaches, capitalizing on the right timing, transformative momentum, and cultural context.
Palantir, whose stock has surged over 400% in the past year, has become a focal point in the AI movement, despite its 20-year history. Similarly, Psy was already a veteran artist in South Korea, having started his career in 1999, 13 years before the global phenomenon’ Gangnam Style’ was released in 2012. The video eventually became the first on YouTube to reach one billion views.
Both share the same superpower: unorthodoxy, which helps them stand out in a competitive field. Palantir has unexpectedly fueled the spirit of AI-driven operations, just as Gangnam Style helped usher in K-pop on a global level. Alex Karp, an unconventional CEO, and Psy, the highly unconventional K-pop artist, embody this spirit of unorthodoxy.
Grappling with Valuation:
As a Palantir shareholder, am I saying this is the “peak” for the company? I don’t know. It seemed things were getting frothy when Palantir surpassed Lockheed Martin’s market cap; now it has a larger market cap than Lockheed Martin, Boeing, and Snowflake combined.
From a price-to-earnings or even price-to-sales ratio perspective, Palantir makes zero sense. While a projected growth rate of 36% is impressive, it falls short of what Zoom Communications achieved during the pandemic or what Nvidia has accomplished over the past three years.
It’s very possible that Palantir’s growth may have already peaked or is nearing its peak. I have little doubt, though, that the company has a long and successful future. However, I am highly uncertain if Palantir can grow enough to meet its sky-high valuation. Any signs of slowing growth could lead to a steep retracement. Any broader market correction or shift in sentiment could lead to a significant decline.
Even though I’m tempted to trim and sell more (if not all) of my shares every time the stock rises, it’s difficult to fight against momentum. Palantir is a profitable free cash flow machine, and its commercial business is in an early growth phase. The story remains compelling. There is little wrong with the actual fundamentals of the company; the focus of late has been predominantly on valuation metrics.
Lessons from Psy:
What Gangnam Style can teach us about Palantir is that a valuation doesn’t have to make sense to justify itself to keep rising. Momentum and narrative transcend numbers (even though Palantir’s numbers are solid).
As T-Pain said, words cannot describe how amazing the music video for Gangnam Style is. The video itself doesn’t make much sense, yet it has dominated globally:
This is an almost Dada-esque series of vignettes that make no sense at all to most Western eyes. Psy spits in the air while a child breakdances, sings to horses, strolls through a hurricane that shoots whipped cream in his face, there’s explosions, a disco bus, he rides a merry-go-round, dances on boats, beaches, in car parks and in elevators and generally makes you wonder if you have accidentally taken someone else’s medication.
I believe the numbers cannot fully capture the actual value of Palantir as a business. My brain struggles to grasp its market cap, and a voice within me says, “This is as good as it will get.” My heart tells me this growth story has a lot more breadth. It has the potential for a longer runway compared to unprofitable companies like Snowflake, CrowdStrike, and Cloudflare.
Perhaps this narrative about Palantir being grossly overvalued could be right and wrong at the same time. In the short term, Palantir is due for an inevitable and painful correction, but proves itself not as a ‘hype meme growth AI stock’ but more akin to a ServiceNow or Microsoft, where they are early in their business lifecycle and maintain a robust growth rate for an extended period.
Palantir’s story shows that powerful momentum can outpace solid fundamentals for a long time. Like Psy’s viral hit, its valuation may defy logic, but that doesn’t mean you sell the whole position. Stay disciplined: believe in the vision, but prepare for volatility.
Reflecting on my own experience, the seismic movement in Palantir’s stock price YTD led me to sell my original cost-basis two years ago. This decision was not made lightly; it seemed reckless not to convert some gains into actual profits.
A few thoughts:
Investing isn’t an exact science. A good story stock with solid fundamentals can sometimes have wild meteoric rises. The talent scouts who discovered Taylor Swift as a teenager probably couldn’t foresee what she would become today. Scouts watching Aaron Judge hit at Fresno State probably did not forecast his ability to hit over 50 home runs and bat over .300 an entire season. Companies can far exceed even the rosiest of expectations because a. the stock market isn’t static, and b. catalysts that propel a stock upward are not visible on a balance sheet.
Palantir has solid fundmantels. Although the upward volatility is similar, it isn’t a “meme” stock in the same vein as Gamestop or AMC. Long-term investors should consider this an investment, not a trade.
The stock is riding on euphoria in the short term, and traders are piling in on the AI wave. Even institutions or “smart money” ignore valuation and are piling in to catch up on AI. There is no way to predict how long this roller coaster ride up will last, but sentiment and “vibes” are variable factors. As good as a company’s fundamentals are, Palantir is punching well above its weight class by almost every financial metric, which creates a situation in 2025 where the actual earnings results won’t justify the current stock price. Investors buying the stock at these prices could be severely disappointed 6-12 months from now with demanding Year-Over-Year comparisons.
Palantir’s market cap has surpassed Lockheed Martin’s (if you are reading this now, it could have doubled), which indicates an overextended stock. Based on revenue and net income, the stock is overvalued today.
Why won’t I liquidate my entire position and try to buy back at a better price? I have a much more long-term mindset and believe Palantir will eventually grow into its valuation. I am willing to ride the inevitable wave downwards but concede that at least some profits need to be taken to build a more significant cash position for the potential of a better buying opportunity in the future.
Company
Q3 Revenue 2024
Net income
Adjusted EPS (USD)
Palantir
726 million
143.52 million
0.10
Lockheed Martin
17.1 billion
1.62 billion
6.80
Looking at the bigger picture:
High stock prices can lead to wildly optimistic, unrealistic expectations where investors do not consider things going wrong.
Cash is the lifeblood of any portfolio. Trying to build a cash position during a downturn is often a reactionary emotional response and not ideal. It’s crucial to maintain a balanced portfolio with a healthy cash position.
Cashing in on 500-1,000% long-term gains can seem like a victory, but I urge investors to be careful. Palantir’s focus on emerging technologies like AI and data analytics positions itself well for future growth. Anyone investing in this company should have patience (which most investors do not have) and a high-risk tolerance. It is overvalued, but the commercial business and AIP are in their infancy. As an investor, Palantir is a rare diamond. It is too valuable to avoid having this cash-compounding multiplier in your portfolio. At the same time, by not selling at least some gains, if the stock were to pull back significantly, it would be as if this rally and your paper gains never happened.
This rapid move-up reminds me of Nvidia from 2016 to 2018. Even for the best-performing company in the world, investors were given windows of opportunity to buy back in at more reasonable valuations later on. I am confident we will have similar retracements with Palantir.
Revolve Group:
The biggest position in my portfolio from a total cost basis, I am optimistic about where Revole is headed in 2025. My stance on the fundamentals of Revolve has remained the same:
It’s not a homerun investment but a solid double
There is no single catalyst to propel exponential growth, and there are no glaring red flags or company-specific risks that would cause me to panic.
Guided by two co-founders with an entrepreneurial vision, no debt, a history of profitability, and a proven business model.
I remain patient because the growth strategy remains intact. Revolve’s biggest competitors are Nordstrom and Macy, legacy companies with the same problem: an inability to attract a Millenial and Gen Z audience. For a luxury department store, this is an existential looming threat.
Big Department store chains have become stale and lack the nimbleness to pivot their business models. Macy’s and Nordstrom likely need to leave the public markets to stay afloat, which is an excellent opportunity for Revolve. While most department stores need to downsize their retail footprint, Revolve’s brand is growing, and its presence in physical retail is just starting.
Some investors may feel this growth story is not appetizing enough, but I see a clear and easy opportunity. Among its e-commerce peers, it’s one of the few growing and GAAP profitable. Revolve isn’t trying to reinvent the wheel, like becoming “The Uber of the Skies” or “Revolutionizing Fitness.” Doing something never done before in investing comes with a higher reward but much more risk. The history of profitability gives me enough assurance to bet that Revolve will be a steadily growing winner.
I am cautiously optimistic. Many analysts are sleeping on Revolve, a small market cap company, becoming an emerging brand set for impressive results in the next decade. Their legacy competitors are in apparent crisis mode. At the same time, most of their e-commerce peers in the luxury industry lack the same financial and brand strength.
Devon Energy:
A position I started recently, Devon Energy, provides great diversity for investors looking to add value and non-tech growth to their portfolio. Oil and gas are highly cyclical commodities, but investors shouldn’t confuse cyclicality with speculation. The price of oil constantly fluctuates. Although oil stocks are sensitive to macroeconomics and geopolitics, Devon is among the best companies in the oil industry.
Reduction of expenses and increase in efficiencies from the Matterhorn Express & Blackcomb Pipeline.
Increase of oil production from the Grayson Mill Energy acquisition.
Dirt-cheap valuation with a strong balance sheet and consistent cash flow.
A company aggressively buys back its stock when said stock is deeply undervalued
An attractive variable dividend that allows investors to be long-term patient.
A “green light” from the Trump administration (less regulation and taxes) that Devon could benefit from significantly.
Companies in the energy sector aren’t every investor’s cup of tea, but building a robust portfolio requires some diversification and value. Although having an asset’s value strongly correlated to oil price may seem risky, investors should consider this a hedging investment rather than just a hedging tool.
I am not a big fan of derivatives or “buying insurance” in your portfolio other than cash. But if you are overweight tech, having an asset that can move up, even with rising interest rates, is quite enticing. Also, suppose you have positions for which you have a deep conviction that you would rather not sell in your portfolio. In that case, Devon Energy can be a great addition to your portfolio because it generates income and will likely rebound when oil prices fluctuate higher. From a long-term viewpoint, the price of crude Oil WTI today is neither high (140.00 in June 2008) nor low (18.84 in April 2020). It could be a good time to start a position in Devon Energy or other oil/natural gas energy companies, with their value being fair-to-good in the near short term.
Pfizer/Moderna:
Every investor has to prepare for the inevitable “truths” that will impact their portfolio: Recessions, pandemics, natural disasters, and geopolitical events are unavoidable and will happen again. Investors must stay disciplined during volatility and take preventive rather than reactionary measures before catalyst events happen. The latest information regarding H5N1 is quite alarming.
My current goal is not to put new money into something already expensive and hope it becomes even more expensive. A long-term investor needs a strategy that fits their goals instead of following a trading strategy and succumbing to behavioral biases of only buying stocks when they go up.
While the market is overweight in AI, I have been building and diversifying my portfolio over the past year by adding energy and biotech.
Pfizer is a more established biotech company that has made a big bet on oncology (cancer). Although the transition has been slow, I expect meaningful breakthroughs with cancer drugs in the next five years.
Moderna carries much higher risk and more significant potential rewards. Its focus isn’t on a specific drug approval but on utilizing AI and mRNA technology to create a “bioplatform.” If it succeeds, Moderna has the potential to unlock the holy grail for pharmaceutical drug companies. Vaccines and drugs that do not have patent expirations (assuming Moderna owns the mRNA vaccine intellectual property). A lot of this comes with unknowns and “ifs” with this bull thesis; however, we already know through data and science that mRNA technology works, and the reward is high (essentially a potential 100x payoff) with probabilities much higher than lottery odds.
Quick hits:
Hims & Her Health—I cannot fully grasp what will give Hims a long-term competitive advantage beyond branding and slick marketing. A brand’s impact on purchasing behavior in apparel works quite differently in telehealth. Your friends and social circle may care what and where you buy your clothes from; I don’t think it matters much with weight-loss drugs and erection pills. I am not bearish on Hims; just unsure how sticky brand loyalty will work in a B2C subscription telehealth platform.
Lemonade—Too early to sell. Investors should wait until Lemonade fully launches its car insurance product nationwide. Unlike most companies I write about, Lemonade has never been profitable. It will stay that way for the foreseeable future. It will remain a small position in my portfolio, but the company seems to be moving in the right direction. Like Roblox, these companies are about a potential story unfolding. The potential reward is a significant return based on a small initial investment. Look at it like a small fire; it could slowly burn or escalate into a major blaze. The stock is volatile and remains higher on the risk scale.
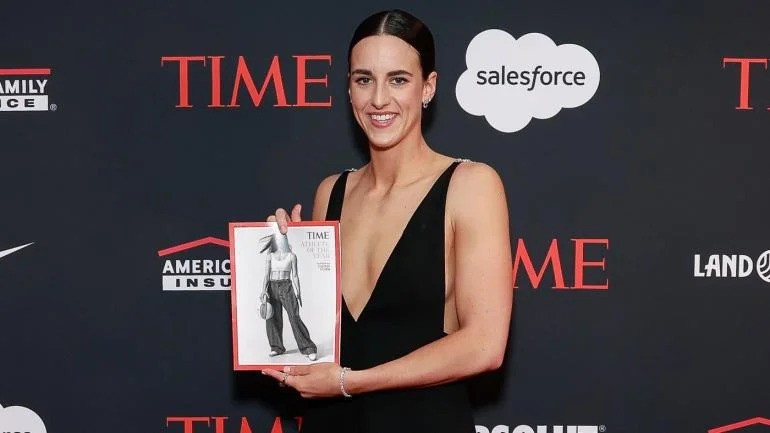
Nike—The turnaround story remains in play. Although sales have declined and the overall brand has stagnated, I am confident that the new CEO, Elliott Hill, can get Nike back on track. Although it seems like a somewhat oversimplified thesis, Nike should benefit from a Caitlin Clark halo effect. Clark was named Time Magazine Athlete of the Year and #100 on the Forbes 100 Most Powerful Women. I believe it is a safe bet Clark will rise up this list, as she is not even at her athletic peak. Clark’s fandom/demand is simmering, and Nike is known to historically promote and market athletes better than any other brand. It will be hard for Nike to screw this up.
Mercadolibre—I remain bullish. Most investors associate Mercadolibre with e-commerce, as it is the most valuable company in Latin America. Its strong infrastructure has created a fortified moat to protect itself from Amazon and other competitors. Next up is becoming the premier fintech bank in Latin America by leveraging its online ecosystem to extend into financial services. Mercardo Pago may never catch up to Nubank; it doesn’t have to. Mercardo Pago is penetrating a large market, and its competitive advantage comes from its ecosystem integration, much like how AWS benefited significantly from its integration with Amazon’s online business. The momentum and growth indicate that Mercado Pago will one day drive most of Mercdaolibre’s operating income, just like AWS does for Amazon. I am not bearish on Nu Holdings, but they are a pure fintech play. In contrast, Mercadolibe has several potential growth levers to pull, making it a superior investment.