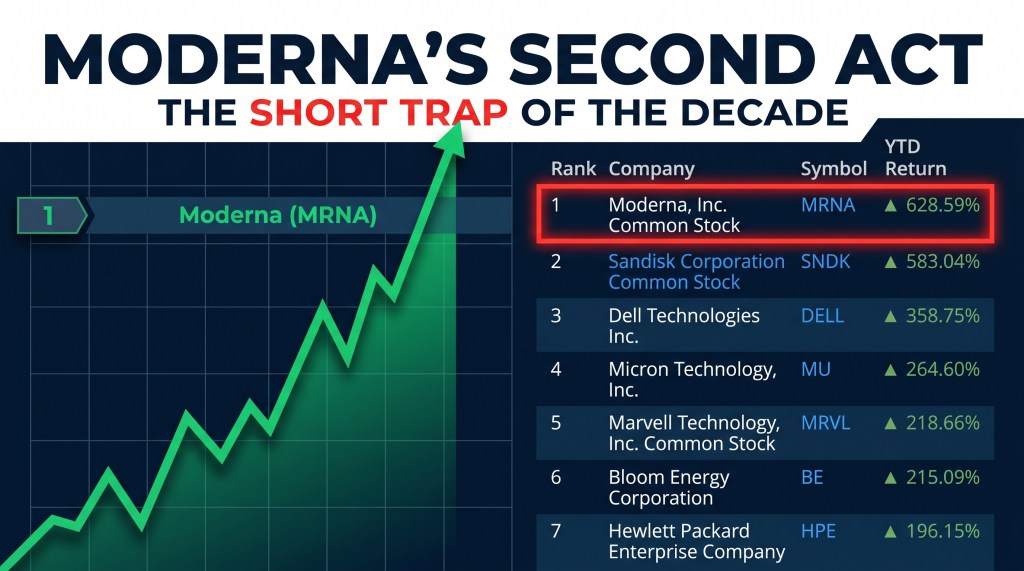
The Short Trap of the Decade: Why Wall Street Still Doesn’t Understand Moderna’s Second Act

Every few years, the financial commentariat suffers from a collective failure of imagination. When a beaten-down stock catches fire, the reflexive reaction from spreadsheet purists is depressingly predictable: dismiss the rally, call the valuation absurd, and hunt for an entry to short.

Right now, that exact mistake is happening in real time with Moderna (MRNA).

Following the Phase 3 topline readout for its personalized cancer vaccine program (reported August 19, 2026; full data presentation at ESMO on October 24), the bears have retreated to a comfortable, lazy narrative:

“It’s just melanoma. It’s an easy target. Other companies have done this before. The valuation has completely detached from reality.”

Every single part of that thesis is demonstrably false.

Trying to undersell Moderna’s Phase 3 data reveals a fundamental misunderstanding of oncology history. Conflating Moderna with speculative, cash-burning micro-cap biotechs is an egregious category error. And attempting to short a paradigm-shifting biotech platform using a static, single-year Discounted Cash Flow (DCF) model is a classic lesson in how accounts blow up.

Here is what the market is actually looking at—and why this run has far more structural power than the skeptics realize.

1. The Historical Myth: “Other Biotechs Have Done This Before”

Let’s dismantle the biggest myth circulating on financial podcasts and social media: the idea that therapeutic cancer vaccines routinely clear Phase 3 trials in melanoma, or that melanoma represents a “low bar.”

In the entire history of cancer immunology, no personalized neoantigen vaccine had ever cleared a randomized Phase 3 trial until Moderna and Merck’s INTerpath-001. Full stop.

For over thirty years, Big Pharma poured tens of billions of dollars into therapeutic cancer vaccines, specifically targeting melanoma because of its high tumor mutational burden (TMB). The result was not a track record of easy wins—it was an absolute graveyard:

  • Canvaxin (CancerVax): A whole-cell vaccine halted mid-Phase 3 in the mid-2000s when vaccinated patients showed zero survival benefit over placebo.
  • MAGE-A3 (GlaxoSmithKline): The massive DERMA trial enrolled over 1,300 melanoma patients targeting shared antigens. It collapsed completely in 2014, failing to improve disease-free survival.
  • Allovectin-7 (Vical): A plasmid-based immunotherapy was obliterated in Phase 3 in 2013 against basic dacarbazine chemotherapy.
  • gp100 Peptide Vaccines: Routinely failed monotherapy Phase 3 trials for decades, eventually relegated to being the baseline control arm that Bristol Myers Squibb outperformed to approve Yervoy.

Whenever bears claim “cancer vaccines have worked before,” they invariably point to two historical outliers that share zero mechanistic overlap with Moderna’s platform:

  1. Sipuleucel-T (Provenge / Dendreon): An autologous cell therapy approved in 2010 for prostate cancer—not melanoma. It targeted a single, non-mutated self-antigen, offered a meager four-month survival extension, was an operational nightmare to manufacture, and entirely failed to translate into a modular platform.
  2. T-Vec / Imlygic (Amgen): An oncolytic herpes virus approved in 2015 for direct, local lesion injection. It is an in-situ lytic agent, not a systemic personalized vaccine, and it repeatedly failed when tested in systemic combination trials with Keytruda across visceral, metastatic disease.

Moderna’s intismeran autogene (mRNA-4157 / V940) achieved what thirty years of oncology research failed to do: prove that an automated digital algorithm can sequence a patient’s unique biopsy, synthesize up to 34 distinct patient-specific neoantigens, deliver them via mRNA, and train a cytotoxic T-cell response that decisively beats the global standard of care in a randomized Phase 3 adjuvant setting.

Traditional oncology fails because when you hit a tumor with a single targeted agent, you may eliminate 95% of the cancerous cells, but the remaining 5% harboring a secondary bypass mutation survive, multiply, and kill the host.

Individualized neoantigen therapy is an algorithmic engine firing 34 distinct polyclonal targets simultaneously. It directly neutralizes cancer’s primary evolutionary weapon—clonal heterogeneity—by deploying patient-specific polyclonal immunity.

Calling this a “low-bar” victory is historical revisionism. It unlocked a biological door the entire pharmaceutical industry spent three decades trying to batter down.

2. The Micro-Cap Delusion: Stop Comparing Moderna to Lab Vendors

A peculiar strain of “circle of competence” distortion happens when micro-cap traders look at large-cap platform companies. Analysts accustomed to screening cash-strapped diagnostics names look at Moderna’s chart and think: “This looks just like a hot penny bio that got ahead of its skis.”

Moderna is not ImmunityBio. It is not GeneDx, Personalis, or Tempus AI.

Those companies operate primarily as diagnostics labs, toolmakers, or single-asset speculative plays. They rely on sample reimbursement, fight commercial insurers over CPT billing codes, and trade at the whim of retail sentiment and thematic micro-cap ETFs.

Most importantly, small biotechs suffer from a fatal structural flaw: the inevitable, momentum-killing dilution. When a sub-billion-dollar clinical biotech spikes 200%, the CFO files an S-3 shelf offering within 72 hours. They have to. They are burning cash with a ticking clock, and survival mandates dumping secondary shares on euphoric retail buyers.

Moderna does not operate under that liquidity trap:

  • The Balance Sheet Fortress: Moderna entered this inflection point backed by a multi-billion-dollar cash cushion built during the pandemic windfall, reinforced by established commercial revenue from its respiratory franchise. There is zero near-term dilution overhang forcing management’s hand.
  • The Merck Partnership & “Boom”: Bears love to scoff that “Moderna only gets 50% of the economics.” That is spreadsheet myopia at its finest. That 50/50 split is with Merck & Co.—the undisputed ruler of the global immuno-oncology market. Merck absorbs half of the staggering Phase 3 clinical trial costs, handles worldwide regulatory filings, and plugs the therapy directly into its global Keytruda commercial infrastructure. Moderna does not need to build a multi-billion-dollar global oncology sales force from scratch.

When the Phase 3 data was unblinded, Dr. Dean Li, President of Merck Research Laboratories, didn’t offer polite corporate PR. He captured the exact magnitude of the shift:

“It isn’t hallelujah. It’s boom.”

That was not the sigh of relief of a gambler hoping for a borderline p-value. It was the calculated assessment of Big Pharma’s sharpest R&D chief recognizing that a thirty-year scientific wall had just been pulverized.

Moderna is an institutional mega-cap asset. It does not belong in a conversation with diagnostic testing labs; it belongs in the conversation with Regeneron, Vertex, and Gilead—large-scale modular platforms capable of self-funding multi-indication expansion.

3. Steelmanning the Bear Case (And Why It Still Fails)

Intellectual honesty demands steelmanning the opposing thesis. The serious bear case was never “melanoma is easy.” The real bear case looks like this:

  1. The Addressable Market in Melanoma is Modest: Resected high-risk melanoma represents tens of thousands of patients annually, not hundreds of thousands. Even with premium orphan pricing, melanoma alone cannot justify an explosive valuation re-rating.
  2. Individualized Manufacturing is Operationally Brutal: Every batch is bespoke (N=1). Biopsy the tumor, sequence the DNA/RNA, predict the optimal epitopes, manufacture a unique mRNA cassette, sterile-filter, and infuse—all within a strict window because adjuvant patients cannot wait months. Turnaround times and high Cost of Goods Sold (COGS) are the traditional graveyard of personalized medicine.
  3. Payer Pushback on High-Cost Regimens: A personalized therapy priced like cell therapy in an adjuvant setting will face grueling prior-authorization warfare and resistance from single-payer healthcare systems abroad.
  4. Keytruda’s Looming Loss of Exclusivity (LOE): Keytruda faces patent expiration around 2028. Because the INTerpath program is anchored on Keytruda combination regimens, biosimilar entry will alter pricing, contracting, and Merck’s strategic incentives.
  5. The Lung Cancer Horizon is Far Away: INTerpath-002 in adjuvant non-small cell lung cancer (NSCLC) carries estimated primary-completion timelines stretching toward 2030. That is a lengthy window to underwrite platform value on faith.

Here is why that steelman still crumbles:

  • On Market Size: Melanoma was never the endgame; it was the biological beachhead. The market is not pricing a single adjuvant indication; it is pricing the platform’s validated right to contest lung, bladder, renal cell, and gastrointestinal cancers. Every subsequent indication is a multi-billion-dollar call option that was violently repriced by Phase 3 proof of concept.
  • On Manufacturing: This is precisely what mRNA was architected to do. Rapid, sequence-to-vial, cell-free synthesis is Moderna’s core competency—demonstrated at planetary scale during COVID. Turnaround times in clinical trials shrank to weeks, not months. Bears are describing an operational barrier that Moderna spent a decade and billions of dollars resolving.
  • On Keytruda LOE: Merck is not sitting idle. Subcutaneous pembrolizumab reformulations protect the franchise, and Merck’s incentive to defend a combination that extends its anti-PD-1 leadership is paramount. An asset that enhances Keytruda’s efficacy is the most lucrative lifecycle-management tool Merck could possess. Biosimilars complicate contracting math; they do not invalidate clinical superiority.
  • On Clinical Timelines: 2030 is distant, but financial markets do not wait for final study completion to adjust discount rates. Equities reprice probability of technical success (PoS) the moment biological feasibility is demonstrated. The adjuvant lung opportunity became dramatically more probable the second INTerpath-001 hit its primary endpoints.

4. Valuation Dogmatism: The Biotech Equivalent of Tesla

Attempting to model Moderna at the dawn of platform validation using a static, single-year DCF model is a fool’s errand.

Moderna is trading like the biotech equivalent of Tesla in 2019–2020.

Back then, legacy automotive analysts opened Excel, divided enterprise value by car deliveries, and shorted the stock into every parabolic run because “the multiple made no sense.” What they failed to grasp was the structural regime shift: the market ceased valuing Tesla as a cyclical capital-intensive automaker and began pricing it as an energy and software platform with near-limitless terminal value.

In biotech, when a paradigm shift occurs, historical valuation anchor points detach completely:

  • Between 2020 and 2021, analysts who claimed Moderna was wildly overvalued at $60, $100, and $150 watched institutional liquidity, index rebalancing, and sheer narrative dominance carry the stock to nearly $500.
  • Look at Vertex Pharmaceuticals during the clinical validation of its cystic fibrosis franchise, or Gilead Sciences during the 2013–2015 rollout of Sovaldi and Harvoni. When a therapeutic platform cures or decisively halts a fatal disease, traditional valuation multiples expand to generational extremes. Generalist institutional funds are forced to buy the equity regardless of valuation simply to prevent career-ending benchmark tracking error.

5. Striking Lightning Twice in Under a Decade

Bears cling to another cynical narrative: “Spikevax was just a temporary pandemic windfall; the sales fell off a cliff, so it doesn’t count.”

That is revisionist nonsense. In pharmaceuticals, a blockbuster is defined by the scale of its real-world impact and the commercial footprint it leaves behind. The cumulative revenue generated by Spikevax made it one of the most lucrative and rapidly scaled commercial therapeutic rollouts in medical history.

Most mid-tier biotechs spend twenty to thirty years praying a single small molecule can clear a Phase 3 study just to stave off insolvency. To pioneer a brand-new technological modality, engineer automated manufacturing from scratch, book tens of billions in commercial cash flow, and then turn around and unlock a historic breakthrough in solid-tumor oncology inside of fifteen years is virtually unprecedented.

Within 11 years of incorporation, Moderna delivered an operational year booking over $17B in top-line revenue, followed by late-stage clinical efficacy across three completely separate branches of medicine within 15 years.

Meanwhile, the commercial respiratory engine continues to quietly execute:

  • In April 2026, Moderna’s mCOMBRIAX achieved European authorization as the world’s first approved flu-plus-COVID combination vaccine.
  • In August 2026, the FDA approved mFLUSIVA—the first mRNA seasonal influenza vaccine cleared in the United States, showing roughly 27% superior relative efficacy over standard-of-care comparator vaccines in Phase 3 trials.

Under normal market conditions, either milestone would dominate Wall Street coverage. Today, they are treated as footnotes. Why? Because the market has caught the scent of something infinitely larger: an individualized immuno-oncology platform backed by Phase 3 data and co-piloted by Merck.

6. The Cognitive Dissonance: When Biology Meets Software

Right now, Wall Street is paralyzed by cognitive dissonance:

  • Tech analysts understand zero-marginal-cost code, software compilers, and network effects, but they freeze because they don’t understand the FDA, hazard ratios, and clinical trial architecture.
  • Biotech analysts understand clinical endpoints, but they are utterly incapable of modeling a platform where melanoma, lung, renal, and bladder cancer all run through the exact same automated manufacturing chassis.

Moderna’s individualized neoantigen therapy is not brewed in a massive remote bioreactor. The patient’s own cellular machinery compiles the synthetic digital code into physical antigens to train the immune system.

When a software update does not require redesigning the underlying CPU, software scales exponentially. Moderna does not need to reinvent chemistry for every new solid-tumor indication; they run the exact same sequencing pipeline, feed the data to the same algorithm, synthesize the same mRNA backbone, and let human ribosomes do the rest.

How big could this be? It has the hallmarks of an exponential paradigm shift—just like when Steve Jobs eliminated the fixed physical keyboard and replaced it with a single sheet of glass running software. Industry heavyweights and analysts relentlessly mocked it at the time. Shorting Moderna today looks like a similarly dangerous mistake.

If you are evaluating this company strictly as another Vertex, Regeneron, or Gilead, you are still thinking too small. The potential could break standard pharmaceutical assumptions the same way scaling compute broke historical hardware limits. The narrative momentum carries the same seismic weight as Moderna during the pandemic outbreak, Nvidia after ChatGPT’s debut, or Eli Lilly opening the GLP-1 floodgates.

7. Conviction Over Consensus

When I first looked at Moderna years ago, I was as skeptical as anyone. A cure synthesized inside your own cells seemed speculative—almost like science fiction. Early on, I even opted for the Pfizer vaccine simply due to the safety of legacy brand recognition.

But an interaction during the height of the pandemic stuck with me: speaking to a frontline grocery worker who was beaming with pride because she had just received her Moderna shot. It sounded emotional and anecdotal at the time, but the underlying truth never left my mind: the platform worked, it scaled under impossible conditions, and it saved lives.

I began accumulating shares of Moderna in 2023, continued buying through early 2025, and have never sold a single share.

My investment thesis was grounded in simple, first-principles logic:

  1. The COVID vaccine was the proof of concept. It proved mRNA could be synthesized rapidly, scaled globally, and translated by human cells safely.
  2. Respiratory combination vaccines evolved Moderna from a pandemic one-hit wonder into a durable commercial platform.
  3. Oncology is Moderna’s second act. Entering the August 19 Phase 3 readout carried immense binary risk, but the structural asymmetry on the other side of validation was generational.

The weight of this position has grown dramatically over the past several months, yet the broader story is only getting started. Skeptics will continue to stare at their spreadsheets, recalculate terminal multiples, and attempt to short into parabolic momentum.

Let them. Stepping in front of an institutionally validated, paradigm-shifting platform armed with positive Phase 3 data, zero dilution risk, the commercial engine of Merck, and violent short-covering mechanics is not financial discipline—it is pure arrogance. The skeptics think this rally is nearing its end; in reality, the paradigm shift is just beginning.

6 Things to Understand About Moderna’s Melanoma mRNA Vaccine

1. This is an Operating System, Not a Pill:

mRNA-4157 (Intismeran autogene) is not a generalized product you pull off a shelf. It is an algorithmic manufacturing pipeline. Moderna and Merck ingest raw, unstructured local data (a patient’s tumor sample), run it through a massively parallel sequencing workflow, and output a customized synthetic mRNA sequence that encodes up to 34 unique neoantigens.

Think of it like this: mRNA-4157 is to oncology what Palantir Foundry is to enterprise software. ChatGPT and Claude are generalized, one-to-many foundational models. Palantir Foundry ingests chaotic, siloed enterprise data and builds a bespoke operational ontology mapping the unique “mutational signature” of a single company. Both platforms operate on the exact same philosophical framework: infrastructure designed for extreme, 1-to-1 mass customization.

This isn’t theoretical. The FDA is literally demanding that Moderna’s machine learning algorithm be submitted alongside the biologic data as part of the regulatory package. The government is treating the software as the drug. You cannot replicate this with off-the-shelf code.

2. Escaping the Blockbuster Patent Trap:

Standard drugs eventually expire and lose their patent exclusivity. Merck’s crown jewel, Keytruda, is essentially the CrowdStrike Falcon of oncology—an incredibly valuable, standard-issue defensive tool. But Keytruda is marching toward a massive patent cliff and facing legitimate, structural competition from Summit Therapeutics.

This is why mRNA-4157 is a massive paradigm shift. Because it is an individualized pipeline, it fundamentally breaks the traditional patent expiration trap. The moat isn’t just a chemical structure; it is the proprietary sequencing algorithm, turnaround speed, and the hundreds of millions Moderna spent building its internal physical manufacturing and software infrastructure. You cannot genericize a bespoke, closed-loop supply chain.

3. BioNTech’s Validation, Moderna’s Execution:

This moment completely validates BioNTech’s foundational thesis, but in biotech, first-mover advantage is everything. BioNTech pioneered the individualized neoantigen concept, but they played it safe. They de-risked their flagship candidate (BNT122) by entering into a deep partnership with Genentech/Roche. By offloading the R&D cost, they ceded absolute control, slowed their timeline, and hard-capped their revenue ceiling.

BioNTech is still grinding through Phase 2 trials for pancreatic and colorectal cancers. Moderna took a highly concentrated approach, absorbed the raw risk, executed faster, and pushed Phase 3 across the finish line years ahead of their rival. In a winner-take-all infrastructure race, BioNTech’s conservative strategy is making them look a distant second-place finisher.

4. The Value is Locked in the IP Trench Warfare:

Do not ignore the legal reality: the absolute value of Moderna and mRNA-4157 is locked in a vicious patent war over the underlying Lipid Nanoparticle (LNP) delivery tech. This is why Moderna pays one of the top legal executives in the pharmaceutical and biotechnology industries, Shannon Thyme Klinger, as their Chief Legal Officer. She is a ruthless, tier-one legal tactician, and her job is to defend the fortress.

Earlier this year, Moderna dropped a staggering $2.25 billion to settle a massive LNP patent dispute with Genevant and Arbutus. Why pay that much? Because controlling the platform IP means controlling the toll bridge for the entire next generation of mRNA therapeutics. Moderna is fighting Pfizer, BioNTech, and Alnylam in a global trench war because if you own the LNP patents, you tax the entire future of the industry. This litigation will dictate who actually captures the long-term margin.

5. The Behavioral Economics of Adoption (Healthy vs. Sick):

We have to separate the underlying mRNA technology from the political baggage of the pandemic. Infectious disease vaccines are inherently a tough sell because you are asking a perfectly healthy person to take a drug that will likely make them feel sick to prevent a statistical probability. It is a breeding ground for political friction.

Oncology completely flips the behavioral economics. You aren’t dealing with a healthy populace; you are dealing with a patient who has had a tumor excised and is staring down the barrel of a lethal relapse. When an individualized therapy can reduce the risk of cancer recurrence by 30 to 50 percent, the calculus is absolute zero: why wouldn’t you take that? The choice isn’t between feeling fine and mildly ill. The choice is between an experimental lifeline and a painful death. This eliminates the political friction and shifts the adoption curve entirely from push to pull.

6. The Peak Revenue Fallacy (The Hunger Games):

Wall Street analysts pricing this asset solely on its “peak adjuvant melanoma sales” are committing financial malpractice. This isn’t just about melanoma. The late-stage data is a proof-of-concept that creates an entirely new therapeutic space for solid tumors. Moderna survived a bloody, decade-long biotech Hunger Games and walked out with the prize.

Retail investors locking in their gains today are going to brutally regret it. If this paradigm shift were a baseball game, we are still in the warm-ups. Would you buy a front-row ticket to the World Series and leave the stadium before the first pitch is even thrown? Selling this news because of near-term scaling costs is missing the forest for the trees. This is a foundational shift in how we treat human disease, and the compounding returns have not even started.

Why Vertex is the Nvidia of Life Sciences

When the market looks at large-cap biopharma, it sees two uninspiring archetypes: bloated, debt-heavy legacy conglomerates milking aging blockbusters, or single-theme obesity plays trading at nosebleed valuations.

What the market fundamentally misprices in Vertex Pharmaceuticals (VRTX) is the biological equivalent of Nvidia’s CUDA ecosystem.

Years ago, Nvidia was dismissed as a high-margin PC graphics chipmaker, while Jensen Huang quietly built a full-stack computational infrastructure. When the AI wave hit, Nvidia didn’t just capture market share; they owned the entire ecosystem. Vertex operates with that exact same first-principles engineering mindset. While legacy pharma treats symptoms with palliative drugs and panic-buys late-stage assets, Vertex is building a multi-vertical platform designed to cure diseases at the causal biological level.

The market continues to penalize Vertex with a “single-franchise discount.” In reality, Vertex possesses a structural sniper edge over every legacy player, and its transition into a five-pillar empire makes a $200B+ market cap the conservative baseline.

The Big Pharma Dilemma vs. The Vertex Edge

Legacy pharma is trapped in a value-destroying cycle. They ride blockbusters into patent cliffs, carry $30B–$60B+ in net debt, and treat acquisitions like lottery tickets—throwing darts at overcrowded spaces to plug revenue holes, which permanently depresses ROIC.

Vertex is the polar opposite. Here is a simple 4-system scorecard that Vertex checks all four boxes.

  • Fortress Balance Sheet: Zero net debt. Its high-margin Cystic Fibrosis (CF) cash engine fully self-funds internal R&D and opportunistic M&A with zero equity dilution.
  • Impenetrable Moat: Vertex’s CF moat is simultaneously biological, clinical, regulatory, commercial, and legal. It became even more unassailable after Sionna Therapeutics (its closest perceived threat) suffered a massive Phase 2 failure in August 2026.
  • Lifecycle Mastery: Instead of waiting for generics, Vertex cannibalizes itself. Rolling out the superior Alyftrek triple reset their composition-of-matter exclusivity past 2039+ before competitors could even establish a clinical foothold.
  • Causal Biology Focus: Rather than chasing 10% market share in crowded spaces, Vertex targets diseases with human-validated causal biology and severe chemistry hurdles. When the biology is clear but brutally difficult to drug, Vertex engineers the definitive solution.

The Core Thesis: A Lone Shark Enters the Ocean

Historically, Vertex was the lone shark in a medium-sized pool (CF) with zero natural predators and total pricing power. The thesis being tested today is what happens when that shark swims into multi-billion-dollar oceans (Pain, Nephrology, Endocrine, Heme).

  • The Base Case (The Conglomerate Floor): Even with moderate pipeline penetration, Vertex’s CF fortress guarantees high-margin cash flows past 2039, solidifying a highly defensive $150B–$180B cash engine.
  • The Bull Case (The 5-Pillar Dominator): If Vertex successfully scales across all five disease pillars, it emerges as a multi-monopoly powerhouse commanding five distinct therapeutic spaces.

The 5 Disease Pillars: 2026 Baseline vs. 2030 Projections

By 2030, non-CF verticals transition from early launches to multi-billion-dollar engines, bringing CF revenue concentration down from ~94% to under 58%.

(Hypothetical 2030 projections assume baseline, safe commercial scaling across late-stage assets. This model excludes future M&A and assigns zero revenue to early-stage moonshots).

Therapeutic PillarCore Program(s) & AssetsCurrent Base (2026 Run-Rate)Projected 2030 RevenueProjected 2030 MixCommercial Role & Pipeline Vector
1. Cystic FibrosisAlyftrek, Trikafta, Symdeko, Orkambi, Kalydeco, VX-828 / NG 3.0~$12.5B (~94.0%)$14.5B~57.5%Base cash spigot; patient conversion to once-daily Alyftrek + next-gen 3.0 triples; IP secured past 2039.
2. Pain ManagementJournavx (acute), DPN (neuropathic), NaV1.7/NaV1.8 combos~$200M (~1.5%)$3.5B~13.9%Non-opioid standard of care; acute surgical launch scaling into chronic neuropathic pain (DPN/LSR).
3. Rare Endocrine (Crinetics M&A + T1D)Palsonify, atumelnant (CAH/ADCS), Zimislecel, Next-Gen Hypoimmune~$120M (Launch phase)$3.0B~11.9%First oral SST2 for acromegaly (Palsonify) + oral ACTH antagonist (atumelnant in CAH/Cushing’s) + early T1D cell therapy.
4. Renal DiseasePovetacicept (IgAN / pMN), Inaxaplin (AMKD), VX-407 (ADPKD)$0 (Phase 3 pipeline)$2.8B~11.1%Dual BAFF/APRIL platform (Alpine) + first-in-class APOL1 inhibitor for AMKD + VX-407 in polycystic kidney disease.
5. Hematology (Heme)Casgevy (SCD / TDT), Next-gen improved conditioning~$180M (~1.4%)$1.4B~5.6%First-in-class CRISPR curative gene therapy; expanding authorized treatment centers and gentler conditioning.
Total Top Line~$13.2B~$25.2B100%~14.1% Top-Line CAGR with CF concentration dropping under 58%.

Why $200B is Just the Warm-Up

Hitting a $200 billion market cap by 2030 requires the stock to climb to roughly $787 per share. That demands a modest ~9% annualized gain—essentially just matching the historical S&P 500 baseline, but backed by zero net debt and inevitable multiple expansion as the single-disease penalty evaporates.

But that valuation assigns absolutely zero weight to Vertex’s asymmetric moonshots:

  1. Type 1 Diabetes (The Functional Cure): Vertex has already proven that fully differentiated stem cell-derived islet cells can restore endogenous insulin production. If their next-gen hypoimmune program evades immune rejection, they don’t just sell a treatment—they own the curative standard of care for millions.
  2. In Vivo Gene Editing: Vertex is aggressively moving toward permanent, one-time in vivo genetic repair. If they crack the delivery mechanism to edit DNA directly inside the body, Vertex transitions from a drug developer into the foundational platform for human genetic repair.

The long biotech winter is over, and legacy pharma is staring down a $300 billion patent cliff by 2030. They are locked in a desperate M&A land grab to replace lost revenue. Vertex with its self-funding CF Monopoly is playing a different game: The slient assassin.They move quietly into high-conviction territory, secure mechanism-validated platforms like Alpine and Crinetics before competitors even wake up, and turn single assets into multi-decade cash engines.

This is exactly why I built a position in Crinetics Pharmaceuticals earlier this year. Crinetics showed all the traits of a “mini Vertex”—focusing on well-understood causal human biology in rare endocrine diseases. The fact that Vertex was the apex predator that recognized that exact value, swooping in to acquire them for $10 billion, validates the thesis: Vertex is the sharpest capital allocator in the space. I will continue to build my position.

Drug development will always be probabilistic, but you are not underwriting a single-asset biotech lottery ticket here. You are buying an impenetrable, high-margin monopoly floor that pays you to wait, with a free call option on a half-trillion-dollar genetic platform.

Zoom: The “Anti-Fragile” Asymmetrical Bet?

“The IT department of every company is going to be the HR department of AI agents in the future. Those digital employees are going to work with our biological ones, and that’s going to be the shape of our company in the future.” — Jensen Huang, CEO of NVIDIA (CES 2026)

If the Godfather of AI is right, the future of work isn’t just better video calls—it’s managing a hybrid human + digital workforce. While the market wrote Zoom off years ago, the company has quietly repositioned itself as the natural “HR Department” for those agents.

Investors are still psychologically scarred. Mention Zoom and the ticker probably triggers 2021 PTSD. Just the mention of the ticker probably feels like a personal attack. Even Cathie Wood fully liquidated her position in late 2023, but what if her investing thesis was correct, just early? While the market is staring in the rear-view mirror, they are missing a fortress balance sheet and a hidden AI stake that could soon rival the company’s entire current valuation.

The Cash Fortress (The Valuation Floor)

Forget the hype. Let’s look at the math. This is where the margin of safety lives:

  • Market Cap: ~$23 billion
  • Cash & Marketable Securities: $7.8 billion (Zero debt)
  • Enterprise Value: ~$15.2 billion
  • Free Cash Flow (FY26): $1.9 billion

You are buying a premium SaaS platform—a global brand with 140k+ enterprise seats and sticky workflows—at ~7.5x FCF. For context, boring hardware companies and legacy retailers trade at higher multiples. The market is pricing Zoom for a slow death, but the cash flow says it’s thriving.

This is the definition of “Dirt Cheap.” Even without a major catalyst, the downside is protected by a mountain of cash and a business that produces liquidity.

The Anthropic Windfall: A “free” Home Run

In 2023, Zoom quietly invested $51 million in Anthropic at a $4 billion valuation. Fast forward to February 12, 2026: Anthropic closed a $30 billion Series G at a $380 billion post-money valuation.

Analysts peg Zoom’s stake at $2.5–$4.5 billion today. If Anthropic IPOs at the rumored $750B+ range this year:

  • The Math: Zoom’s stake could hit $10 billion+.
  • The Proxy Play: Amazon owns more of Anthropic, but because AMZN is a $2.5T behemoth, the stake only moves their needle 3-5%.
  • The Impact: For a giant like Amazon, that’s a rounding error. For Zoom, it’s nearly 50% of its current market cap. When you buy Zoom today, you aren’t just buying a software company; you’re buying a massive, liquid stake in the leading “reasoning” AI- for almost nothing.

The Gen Z Factor & The “War Chest”

As Gen Z enters the C-suite, the “Microsoft-only” era is fading. 2026 data show that Gen Z and Millennials (who now make up over 60% of the workforce) prefer the low-friction and video-first nature of Zoom. They want a “System of Action,” not a “System of Record.”

The Competitive Advantage (vs. Salesforce/CRM): CRM is a giant, but it has virtually no cash compared to Zoom’s hoard. Zoom is lean, founder-led, and has a $7.8B war chest to acquire high-growth AI startups to force that return to 15% revenue growth.

The “Anti-Microsoft” Pivot: The Orchestrator of AI

The bear case is simple: “Microsoft Teams is free, so Zoom is dead.” But the data shows a “David vs. Goliath” moment is happening in the Enterprise:

  • Enterprise Revenue: Grew 7.1% last year (Q4 FY26), triple the rate of the small-biz segment.
  • The Fortune 10 Win: Zoom recently displaced Cisco in a 140,000-seat deal. Why? Because giants are tired of “Microsoft Lock-in.

The Federated AI Approach: While Microsoft locks you into OpenAI, Zoom’s AI Companion 3.0 is a “conductor.” It switches between Anthropic (Claude), OpenAI (GPT-5), and its own Small Language Models in 0.1 seconds. It’s “Best-of-Breed” vs. “Whatever Microsoft bundles.”

MetricSalesforce (CRM)Zoom (ZM)Why This Favors Zoom
Market Cap~$179.7B~$25.3BLower Bar: Easier for a $25B company to 2x than a $180B giant.
Net Cash$8.4B$7.8BAcquisition Firepower: Zoom’s cash is 30% of its market cap. CRM’s is only ~4%.
Enterprise Seats~150,000 Companies~220,000 CompaniesUpsell Runway: Zoom has more “doors” to walk through to sell Phone/AI/Contact Center.
AI/Agent DisplacementHigh RiskLower RiskSalesforce relies on “human” seats (Sales/Support). Zoom’s video/phone is “infrastructure.”
Debt Load$7.6B$0Flexibility: Zoom has zero “interest rate heartburn.”

Why Zoom Wins the “Agent” War Yuan Saw First

While Salesforce’s Marc Benioff spent 2025 screaming about “Agentforce,” Eric Yuan was already there in June 2024. In his Decoder podcast interview nearly two years ago, Yuan laid out a “prophetic” vision of “Digital Twins.” He envisioned AI agents that don’t just summarize meetings but attend them for you, negotiate contracts on your behalf, and make decisions based on your specific “First Principles.”

At the time, the market laughed it off as sci-fi. Today, it is the north star for the entire industry. Zoom wins here because:

  • The System of Action: AI agents don’t want to navigate 20 layers of a legacy CRM. They want to “join the meeting,” take notes, and execute tasks. Zoom is where the work actually happens.
  • The Switzerland of Tech: Zoom doesn’t force you into one LLM. Your digital twin can pick the best engine without vendor lock-in.
  • Zoom Phone just crossed 10 million paid seats. It’s the “wedge” that’s breaking open massive platform deals.

Rare Asymmetry with Minimal Capital Risk

This is a very clean, asymmetrical setup in tech. Zoom doesn’t need Microsoft or Salesforce to implode. It doesn’t need another pandemic. It just needs a founder-led company with a history of delivering during uncertain times to keep executing and achieving a very attainable 10-15% growth rate. Even a 20-30% growth, though wishful, is not delusional.

The Risks? This thesis will be tested. The primary risk here isn’t the total loss of capital—at 7.5x FCF, the floor is remarkably solid. Instead, the risk is opportunity cost. We don’t know how long it will take for the market to wake up and re-rate this “pandemic relic” into a “2026 AI powerhouse.”

In my view, the risk of losing principal is surprisingly low, but the patience required to see the thesis materialize is high.

Disclosure: I am not bearish on Microsoft; in fact, I own shares in MSFT. I am not bearish on CRM (Salesforce), though I currently own no shares. I simply believe Zoom is a mispriced anomaly hiding in plain sight.

The Duolingo “Lizard Brain” Liquidation: Why Retail Is Wrong Again

This is exactly why the average retail investor consistently underperforms the S&P 500: they are biologically wired to buy high and sell low.

We are currently witnessing a classic “Retail Doom Loop” with Duolingo (DUOL). If you’re staring at the price ticker instead of the fundamentals, you’ve already lost the game.

Your Biology Is Your Worst Enemy

The “lizard brain” (the amygdala) is a marvel of evolution designed to keep you alive, not to make you wealthy.

If your tribe started running 50,000 years ago, you didn’t pause to ask, “Is that a lion or just a technical correction?” You ran. In the wild, that is survival. In the markets, that is financial self-destruction.

  • The Tribal Sell: The stock drops 20% in a week → your lizard brain screams, “The tribe is fleeing! There must be a predator (AI) I can’t see!”
  • The Narrative Pivot: Loss aversion (we feel the sting of losses roughly 2x more than the joy of gains) forces us to rewrite history. We don’t say “the price is lower.” We say “the company is failing.” It’s emotional pain relief dressed up as “analysis.”

The Retail Loop of Doom

Retail investors rarely buy value; they buy social proof. Here is how the loop destroys portfolios:

  1. The Validation Phase: Retail ignores the stock while it’s quietly forming a base. They only jump in after a +40% rally because “the price action proves it’s good.”
  2. Conviction Evaporation: Because the thesis was built on a green line moving up and not fundamentals, the very first red candle triggers panic.
  3. The Narrative Flip:
    • Price Up: “Luis von Ahn is a genius; the owl is the future of AI.”
    • Price Down: “The app is a fad; AI is disrupting them; the CEO is distracted.”

This is reflexivity at its most toxic: price shapes mood, mood shapes selling, and selling drives the price lower until the entire tribe has fled the cave.

Prisoners of the Moment

The current wave of hate toward Duolingo isn’t analysis—it’s emotional venting from people who bought near the $500+ peak in May 2025 and are now feeling the burn. They are prisoners of their own portfolio pain, not the reality of the business.

If you’re “hating” the company today, ask yourself: Were you investing, or were you gambling with leverage and money you couldn’t afford to lose? Your anger isn’t with the green owl. It’s with your own risk management.

The Irrelevance of Anchoring

“I bought at $500, so I need it to get back there to be ‘right.’”

Your entry price is 100% irrelevant. The past transaction cannot be undone. All that matters is what the business is worth today versus its future potential. If you overpaid for a great house in a bidding war, the house didn’t suddenly become “bad”—you just paid a premium for a premium asset.

The market is currently offering Duolingo shares at a 70–80% discount to the peak. I’m betting this is normal growing pains, not an irreparable decline. No great company avoids “off years.”

I very much could be wrong but my cost basis and holding period is unique to me. I am comfortable with the risk, and that’s all that matters.

Pivot from Strength: The Agility Advantage

Ignore the stock price for a minute. Duolingo is acting from a position of extreme strength. Compared to the “supertankers” of digital media, Duolingo is a nimble speedboat.

CompanyMarket CapEmployeesThe “Agility” Factor
Duolingo~$4.7B~850Speedboat: Can pivot the entire roadmap in a month.
Spotify~$106B~7,300Tanker: Massive scale, but harder to maneuver.
Netflix~$406B~16,000Supertanker: Incredible reach, but heavy overhead.

From first principles, it is infinitely easier for Duolingo to pivot its roadmap to AI-native learning than for these behemoths to turn their ships. Focusing on user growth over immediate monetization is the correct long-term move, even if it causes short-term “earnings heartburn.”

Planting vs. Harvesting

Wall Street is throwing a tantrum because Duolingo is “foregoing” more than $50 million in bookings to remove ad friction.

The contrarian view? They aren’t losing money: they’re reinvesting in distribution. They are betting that a network effect of 100 million daily active users (DAUs) will be worth far more than squeezing a few extra bucks out of frustrated free users today. They are trading short-term harvesting for long-term dominance.

The AI “Barrier to Success”

In a world where everyone has GPT-4, the winner isn’t the one with the “best” AI, it’s the one with distribution, brand, and proprietary data. Duolingo has billions of data points on how humans learn and a owl brand that is a global cultural icon. They aren’t being disrupted; they are the disruptors. They are using their $1.04 billion cash pile and a new $400 million buyback to repurchase shares while the lizard-brain crowd hands them over at a massive discount.

Final Thoughts:

I’ll concede this: if you signed up for a quiet, slow-and-steady compounder, DUOL isn’t for you. Luis von Ahn is in “Full Founder Mode,” and that makes some shareholders uncomfortable.

But if you have an appetite for volatility and believe in the long game, this is a prime investment candidate for a Roth IRA. The potential gains are astronomical—and entirely tax-free.

Stop confusing a high-volatility stock with a risky company. They are not the same thing. If they hit 100M DAUs by 2028, buying DUOL near a $4.7B valuation today will look a lot like buying Netflix in 2011. Forget your entry price and the stock price. Focus on the compounder.

Duolingo: The Fake Sentiment Crisis

The market currently treats Duolingo like a “dead app walking,” terrified that AI will turn language learning into a relic. They are playing the math of a utility company while ignoring the psychology and network effects of a platform. The argument that Duolingo is headed to zero is dumb. The argument that AI language tools make learning a new language obsolete is even dumber.

Part 1: The Blackjack Blunder (Panicking Over a 6)

In Blackjack, if the dealer is showing a 6—the statistically weakest card in the deck—and you are sitting on a Soft 18 or a 7, you don’t surrender. You double down.

  • The Table Panic: Right now, the market is “surrendering” because they are convinced the dealer has a King or an Ace hidden under the cards. They are sweating over a ghost.
  • The Reality: The dealer (the bears) has a weak hand built on vague fears about AI. Meanwhile, your hand is a 40% revenue grower with $1.1 billion in net cash and zero debt. The market is surrendering a winning hand because it’s spooked by a bust card. When a stock is down 70% from its high, but the business is still growing revenue at 41%, the market is no longer pricing the business on facts—it’s pricing it on fear.

Part 2: Dirt Cheap—The Valuation Gap

The quants are missing the forest for the trees. Let’s look at the actual damage:

  • The “Gift” Multiple: Duolingo is trading at an EV/Sales of ~4.2x. For a 40% grower, that is an absolute anomaly. Most software companies growing this fast trade at 8x to 12x revenue.
  • The Cash Rebate: With $22 per share in net cash, you’re buying a world-class growth engine at a “distressed asset” price.

Part 3: The Platform Moat (Robinhood, Spotify, and Bad Bunny)

Comparing Duolingo to titans like Meta or Netflix might be a stretch in scale, but the logic is identical: platforms that own the “habit” win.

  • Engagement is a Moat: In Q3 2025, Duolingo crossed the massive milestone of 50 million Daily Active Users (DAUs), growing 36% YoY. People aren’t just downloading the app; they are addicted to it. A translation tool is a utility; Duolingo is a habit.
  • The Spotify/Robinhood Parallel: Remember 2022? The “smart money” said Spotify was dead because of Apple Music. They said Robinhood was a “zero” because of Fidelity. They were wrong. They ignored the UX and the habit. Same with edtech rivals like Babbel or Rosetta Stone. Duolingo’s network effects (social sharing, leaderboards) make it the iPhone of apps: sticky in a way pure utilities aren’t. AI might commoditize translation, but it can’t commoditize community. Duolingo has 100M+ total users sharing streaks; that’s a flywheel no chatbot can spin alone.
  • The 35% Spike: Look at the “Bad Bunny Effect.” Following his Super Bowl LX appearance, Duolingo saw a 35% week-over-week spike in Spanish learners. People don’t just want to “understand” culture; they want to participate in it.

Part 4: The “Utility Fallacy” (Why AI Can’t Kill Art)

The argument that AI translation makes learning a language obsolete is the single dumbest take in modern tech. It treats language as a “data transfer” problem, ignoring the soul of human behavior.

  • Language = Social Status: Treating language like a pure utility is an enormous misreading of human nature. Just like food is more than just fuel, and the clothes you wear go beyond just functionality, language is a signal of effort, intelligence, and respect.
  • Soul Can’t Be Translated: People don’t listen to Bad Bunny because they need to translate his lyrics into a technical document. They listen because they like the music, the rhythm, and the slang. You don’t learn a language to “get the data”—you learn it to inhabit the soul of the culture.
  • The Attraction Factor: A survey found that 79% of adults find bilingualism more attractive than monolingualism. Using a translator app to impress someone you’re attracted to has zero “oomph.” It’s the difference between a “fancy restaurant” and “buying ingredients at the store.”
  • The Restaurant Logic: Saying AI kills language apps is like saying people will stop eating at restaurants because groceries are cheaper. We don’t eat out for the calories; we eat out for the experience and the connection.

Let me be clear: Those arguing that AI will turn language into a utility are engaging in one of the silliest “intellectual” debates I have ever heard. It is shockingly ridiculous. It assumes humans are robots that only care about the shortest path from Point A to Point B. In the real world, we take the scenic route because that’s where the value is. And here’s the kicker, bears forget: Duolingo is AI. They’re building the moat higher while rivals play catch-up. Their Duolingo Max tier (powered by GPT-4) rolled out AI-driven “Video Call” and “Roleplay” features last year, letting users practice real conversations with an AI that adapts on the fly. It’s not replacing the habit; it’s supercharging it.

Part 5: The 5-10x Opportunity (The Bottom Line)

Investing is most rewarding during difficult times when sentiment is at its lowest. Even if you don’t believe Duolingo returns to its peak 45x revenue multiples, this is an opportunity worth taking. With earnings dropping on February 26 (just two weeks out), hint at it as the “next card flip.”

  • Asymmetric Risk: the downside is protected by a billion-dollar fortress.
  • The Path to $1,000: For Duolingo to reach $1,000, it needs to become a $47 billion company. In the tech world, that’s just a “successful mid-cap”—the size of Workday or Lululemon. Given its AI-powered “Personal Tutor” narrative, this is a very plausible outcome over the next 5-10 years.
  • I started a position last week. An opportunity based on a SaaS apocalypse, which feels irrational given that Duolingo is not even a SaaS company. I will look like a visionary or an investor in complete denial.

The Verdict: You’re being offered a “Royal Flush” opportunity. By the time the math proves Duolingo is a $50 billion company, the stock will already be at all-time highs. Betting against the Owl is betting against human nature. I’ll take the other side of that trade every time.

Lemonade’s Moment of Truth: From Speculation to Generational Play

The Mainstream Blind Spot

Most investors are still fixated on the smoking crater of the 2022 bubble. They haven’t refreshed their mental models to reflect Lemonade’s evolution from a cash-burning startup to a data-driven compounding machine. That lingering skepticism? It’s pure alpha.

The Pivot to Profitability

Lemonade has long been a tantalizing story, but the big “if” was always profitability. Now we’re witnessing the “how.” The narrative has flipped from raw growth to ruthless operational efficiency. Key highlights from Q3 2025:

  • In-Force Premium (IFP): Reached $1.16 billion, up 30% YoY—their 8th straight quarter of accelerating growth.
  • Loss Ratio Mastery: Gross loss ratios have plummeted from 73% down to 62%. In insurance, that 11-point swing is the difference between a straw house and a fortress.
  • Efficiency at Scale: Loss Adjustment Expense (LAE) ratio—the cost to process claims—dropped to 7%, below legacy players like Progressive or Geico (typically 9-10%).
  • Reinsurance Revolution: Primary quota share ceded fell from 55% to 20%. Lemonade’s finally retaining the “juice” instead of outsourcing most profits to reinsurers.

The Coiled Spring: The Tesla Shot of Adrenalin

A coiled spring demands a spark. Enter the Autonomous Car Insurance launch: Arizona on January 26, 2026, and Oregon in February. By plugging directly into Tesla’s Fleet API, Lemonade delivers ~50% per-mile discounts with Full Self-Driving (FSD). This isn’t just insurance; it becomes a viral customer magnet.

  • The “X” Factor: Tesla influencers’ publicity and Elon Musk’s orbit have generated millions of organic impressions. In a world where a Super Bowl ad costs $7 million for 30 seconds, Lemonade effectively ran a “digital Super Bowl campaign” for free.
  • The Safety Edge: Lemonade’s data shows FSD-assisted driving is roughly 2x safer than human driving. They are pricing risk with high-resolution telemetry that traditional insurers simply can’t touch.

The 10x Revenue Multiplier

The hidden gem? Premium per Customer is now $403 (up 5% YoY). As the “Lemonade generation” matures from $15/month renters to $150/month car/pet/home bundles, revenue per user could 10x while acquisition costs hold steady. It’s the flywheel legacy insurers envy.

The Bottom Line

I am extremely bullish. This isn’t the same as buying the hype at 70 in 2020. Over 5 years later, the company is dramatically more efficient, and “Car” is a proven engine rather than a theoretical startup.

The Lemonade thesis was never about a sleeker app; it was about a fundamentally superior information architecture. While the legacy giants like State Farm or Geico price based on broad ‘buckets,’ Lemonade is finally proving it can price at the individual level.

With the stock retracing under 70 (currently hovering around $63–$64 after a volatile start to the year), we may be in the final throes of disbelief. Q4 2025 Earnings Call on Feb 19th is just days away. The data is trending toward a triple-threat: accelerating growth, massive margin expansion, and a clear path to profitability. With the recent winter storms being less catastrophic than feared, the pathway for Lemonade to run in 2026 and 2027 is wide open.

The Clothing Company Outperforming Nvidia

Aritzia’s Q3 FY2026 was one of its best quarters ever—like a walk-off home run in the playoffs. For the first time in the company’s history, they crossed the CAD 1 billion revenue mark in a single quarter, hitting CAD 1.04 billion, up 42.8% YoY.

Aritzia grew sales by nearly 43% while increasing inventory by only 10%. This means their inventory turnover is accelerating and they’re selling clothes almost as fast as they can get them off the trucks. This leads to fewer markdowns and higher full-price selling, which is exactly why their gross profit margin expanded by 30 basis points to 46% this quarter. This 4.3x “Sales-to-Inventory” growth ratio suggests an operational efficiency that makes even the “Mag Seven” look sluggish.

Compare that to Lululemon: Their inventory grew by 11%, but revenue only grew by 7%. When inventory outpaces sales, it usually leads to one thing: markdowns. In fact, Lululemon’s Q3 earnings call explicitly noted that gross margins were squeezed by higher markdowns (up 90 basis points) and tariff impacts. They have ~$2 billion in yoga pants and gear sitting in warehouses that they’re struggling to move at full price.

Aritzia is actually running a more efficient operation relative to its growth than even Nvidia right now. Here’s a quick side-by-side:

CompanySales Growth (YoY)Inventory Growth (YoY)Ratio (Sales/Inventory Growth)
Aritzia42.8%10%~4.3x
Nvidia62%~32% (9M cumulative)~1.9x
Lululemon7%11%<1x

Aritzia’s ability to scale this aggressively while staying so disciplined on inventory is retail execution at its finest, turning hype into real, high-margin momentum. If you’re looking at consumer discretionary winners in this environment, Aritzia is flexing harder than most realize.

This quarter also saw the late-October launch of the Aritzia Mobile App, which hit 1.4 million downloads and became the #1 shopping app in North America on day one. E-commerce revenue surged 58.2%, proving that “Everyday Luxury” translates perfectly to a high-frequency digital experience.

In 2027, Aritzia isn’t just signing a lease; they’re opening a new 40,000 square foot flagship store of the former Nordstrom footprint in Vancouver’s CF Pacific Centre. Aritzia is officially planting its flag on the grave of the defeated old guard.

This is the coronation of a new king. It marks the definitive shift from the bloated, “everything-for-everyone” department store model to a new, aggressive power dynamic. Aritzia has engineered a psychological moat known as “Everyday Luxury.” This isn’t just fashion; it’s a socioeconomic pivot that captures the soul of the modern consumer:

  • High-End Design: The clothes look like they belong on a Paris runway (minimalist, high-quality fabrics, tailored fits).
  • Attainable Pricing: Because they control the supply chain, they can sell that “look” for $150–$400 instead of $2,000. By pricing themselves 30–40% below heritage luxury (The Row, Celine) but 20–30% above fast fashion (Zara, H&M), they’ve created a “sweet spot” of attainable exclusivity.
  • The Result: They’ve captured the “HENRY” (High Earner, Not Rich Yet) demographic. This group is remarkably resilient to macro downturns because they view Aritzia as a “reasonable” yet “necessary” indulgence rather than an extravagant splurge.
  • The Psychology: Since “big” milestones (real estate, stable pensions) are increasingly out of reach for many, the HENRY demographic is reallocating their discretionary cash into “micro-luxuries” that provide immediate status and emotional ROI.

As we are witnessing with Saks, the “department store” represents the old middle class: a place where you go to see a little bit of everything. It’s a dying generalist model in a world that’s increasingly specialized.

  • The Old Way: Middle class = Access to variety.
  • The New Way: Middle class = Access to a vibe. Aritzia doesn’t just sell clothes; it sells a lifestyle aesthetic. When you walk into their “Super Flagships,” you aren’t shopping; you’re participating in a brand-curated experience.

The stock is trading at record highs with a P/E that reflects “perfection.” But Aritzia is just hitting its stride. They’ve successfully moved beyond “leggings and hoodies” into a full-wardrobe solution. It isn’t just superb execution by management; it’s capturing the vibe of today’s consumer.

I bought the stock as a small position in 2023 and have held it and will continue to hold it. If we’re using a baseball analogy, we are still very early. For Aritzia’s growth, we haven’t even entered the 7th inning stretch. Aritzia currently has roughly 72 boutiques in the US (out of 139 total). For context, Lululemon has about 374 stores in the US. Aritzia’s stated goal is ~150 boutiques total by 2027, with long-term potential for 180- 200+ overall, focusing heavily on US expansion (8-10 new boutiques annually, mostly in the US). If Aritzia hits its 150-store near-term target, revenue will likely triple as brand awareness hits a tipping point.

I am officially pegging Aritzia as a stock to buy during a market correction or pullback. Unlike legacy retailers, Aritzia is currently expanding its US footprint into a demographic that views “Everyday Luxury” as a non-negotiable part of their personal identity. This psychological moat, combined with an operational efficiency that is scaling faster than its infrastructure costs, makes Aritzia uniquely qualified to weather consumer weakness better than almost any peer in the sector.

If the market gives me a discount on this level of execution, I’ll take it.

Investment Thesis: LA Chargers 2026–27 Championship (Prediction Market Play)

Asset Class: NFL Event Contracts (e.g., Robinhood, Kalshi)

Time Horizon: 12–14 Months

Conviction Level: High (Conditional on Jesse Minter’s retention)

I. Executive Summary

The market will likely misprice the LA Chargers due to recency bias following their 16–3 Wild Card exit. By applying first principles, I identify a massive gap between the “Playoff Loser” narrative and the reality of a team with elite QB talent, a top-tier coaching foundation, and the league’s most aggressive potential for capital deployment in 2026 ($103M+).

II. The Prediction Market Edge: Trading the Probability Curve

Unlike traditional sports betting, prediction markets function like tradable securities. This creates two distinct exit windows before the Super Bowl even occurs:

  • The “Offseason Alpha”: If the Chargers land a Tier-1 Center (e.g., Tyler Linderbaum) and the market sees a healthy Joe Alt/Rashawn Slater in camp, the contract price will spike. A $0.05 entry in March could trade at $0.15 by August—a 3x return without a single game played.
  • The “Hot Start” Multiplier: A 4–0 start against a regressing AFC field could move that contract to $0.25+. I can harvest gains based on sentiment shifts rather than holding for the final outcome.

III. The Fundamentals: Mean Reversion & Liquidity

  1. The “Stabilized Wall”: The 2025 season was a statistical outlier for O-line injuries. The return of Alt and Slater is a “built-in” upgrade that requires zero cap spend. When Alt was on the field, Herbert’s EPA per pass was Top 3. Without him, it was Bottom 4.
  2. The Quarterback Signal: Justin Herbert won 11 games in 2025 with a fractured hand and 54 sacks. He is a “distressed asset” that will revert to elite efficiency the moment the pocket is clean.
  3. The $103M War Chest: The Chargers are in “Rare Air”—a winning team with a Top-5 QB and the #1 effective cap space in the NFL. While rivals (Ravens, Bills, Chiefs) are shedding talent to survive, the Chargers are the primary poachers for blue-chip free agents. After the Chargers, the next team with the most cap space is the Tennessee Titans (money with no pilot for the plane), and the Las Vegas Raiders, an unmitigated disaster.

IV. Risk/Reward: The “Minter” Trigger

  • The Risk: DC Jesse Minter is currently the hottest HC candidate on the market (requested by Browns/Titans/Raiders).
  • The Play: Because HC hires finish in Jan/Feb, the “Minter Factor” will be fully known by the time Robinhood lists the 2027 contracts in mid-February.
  • High Conviction: If Minter stays, the defensive “Floor” remains the best in the AFC. This becomes a “Back the Truck Up” bet.
  • Potential nothingburger: If Harbaugh hires a high-level “CEO-style” DC, the loss of Minter is minimized.
V. Trade Strategy
  • Entry: Late February 2026 (Post-Super Bowl LX listing).
  • The Catalyst: Signing Tyler Linderbaum (C), Trey Hendrickson (Edge), or George Pickens (WR).
  • The Exit: Scale out 50% of the position if the contract 3x’s by the end of the preseason; let the rest ride on the 2027 playoff run.
Conclusion and Closing Thoughts:

Jim Harbaugh and GM Joe Hortiz walked into a burning building in 2024, stayed inside to put out the fire for two years, and have now emerged with a pristine balance sheet.

In value investing terms, they performed a “Distressed Debt Restructuring.” They inherited a team where the “Enterprise Value” (Justin Herbert) was being suppressed by massive, underperforming liabilities.

Two years later, the massive “ball and chain” contracts are all officially off the books. Harbaugh spent 2024 and 2025 eating the “Sunk Costs” of the previous management. He let the stars walk, took the dead money hits, and played the “short game” to win the “long game.”

The Chargers are the AFC’s only legitimate liquidity outlier. They possess the unique balance sheet capacity to absorb a whale like Myles Garrett while simultaneously aggressively stacking Tier-1 free agents. They aren’t just building a roster; they are “buying” a championship window that the rest of the AFC is structurally locked out of.

The market remains inefficient, failing to discount a revamped offense protected by a healthy, elite line. The delta between the Chargers and the “elite” tier is a paper-thin margin that disappears the moment these off-season acquisitions hit the turf.

Barring a catastrophic Herbert injury or a “black swan” medical season, the risk-reward here is heavily skewed. The contract price will likely be mispriced. I’m long, and I’m confident for my first-ever prediction market bet.

Revolve’s Superpowers: A Rare and Powerful Combination Most Investors Completely Overlook

Revolve Group (NYSE: RVLV) is the forgotten champion of apparel retail. While Wall Street obsesses over hyper-growth names and retail investors chase the next meme stock, Revolve quietly operates one of the strongest, most defensible business models in the entire consumer sector. It’s dismissed as “just another overpriced clothing seller,” but that superficial take misses two genuine superpowers that are extraordinarily rare in the apparel sector. This unique combination creates a company that is antifragile in a brutal, cyclical, low-margin industry, a combination that deserves far more attention than it gets.

Superpower #1: A Pristine, Fortress-Like Balance Sheet

Revolve has more cash and cash equivalents than total liabilities. This isn’t total assets minus liabilities. This is cash-on-hand exceeding all debt. As of September 30, 2025, Revolve held $315 million in cash, with total liabilities of just $226, leaving it net cash positive by nearly $90 million. (Revolve Group Announces Third Quarter 2025 Financial Results, 2025) In an industry notorious for leverage-fueled boom-and-bust cycles, this is almost unheard of. Look at Revolve’s closest competitors and legacy apparel names:

  • The RealReal → Negative net cash, drowning in $500+ million of debt
  • Victoria’s Secret → $4 billion in long-term debt, with cash covering only a fraction.
  • Guess? → Leveraged with debt-to-equity over 2x
  • Macy’s, Kohl’s, Abercrombie in their prior incarnations → Perpetual debt refinancings amid endless store closures

Most apparel retailers use leverage as oxygen. Revolve doesn’t need it. Zero net debt (actually net cash) gives them a massive margin of safety that investors in this sector are simply not accustomed to. In a downturn, Revolve can keep the lights on indefinitely without ever visiting a bank. In an upturn, they can aggressively buy back stock (they’ve already repurchased over 20% of shares outstanding since their 2019 IPO, including $100 million authorized in 2023), or acquire distressed brands/competitors for pennies on the dollar. Having such a fortress balance sheet creates real optionality.

Superpower #2: Consistently Elite Gross Margins (54% and Climbing)

The average apparel retailer scrapes by with gross margins of 30-50%. Revolve delivered a 54.6% gross margin in Q3 2025 (up 350 basis points YoY) and has maintained a 50-55% gross margin range for years. For context:

  • Louis Vuitton (LVMH) → 66%
  • Lululemon → 59%
  • Zara → 55-57%
  • Most everyone else → 30-45%

Revolve is operating at the same rarefied level as the very best branded apparel players on earth, despite being a pure-play online retailer without a physical-store crutch. Why does this matter so much? Because elite margins are Revolve’s ultimate defense against Amazon. Retail investors see “expensive clothes” and assume the model is fragile. In reality, those premium prices are the moat. Millennials and Gen Z raised on Instagram and TikTok aren’t shopping for the cheapest white t-shirt: they’re buying an identity, or an outfit that photographs well at Coachella. Revolve sells social currency. Customers happily pay 2–3 times more for the outfit that might cost less elsewhere because they’re paying for curation, discovery, and status. That willingness to pay a premium is exactly what produces 54%+ gross margins and sustains an average order value of $306 in Q3 2025 (up 1% YoY).

And those margins are what keep Amazon at bay. Amazon dominates commodity fashion: fast, cheap, endless selection. If Revolve ever tried to compete on price, Amazon would crush them with its scale and logistics. But Revolve isn’t playing that game. They’re playing the art of the brand premium game, something Amazon isn’t going to win. Even after 25+ years and billions invested, Amazon has failed to crack premium or luxury fashion in any meaningful way, with a fashion gross margin hovering around 20-30%, far below the industry standard. Jeff Bezos himself has admitted that building a real fashion brand is one of the few things Amazon hasn’t figured out.

The Rare Combination

Put the two superpowers together, and you get something compelling:

  • A net-cash balance sheet → survives any storm, buys back stock aggressively, and is opportunistic with M&A.
  • 54%+ gross margins → funds growth, defends against Amazon, produces torrents of free cash flow (up $265% YoY to $59 million in the first nine months of 2025.
    • This defensive balance sheet and offensive margin profile is the definition of antifragile in retail.

Revolve is clearly doing something different: one that builds on digital and social infrastructure to erect a curation and brand moat. They sell the Revolve experience, which allows them to charge premium, full-price prices (high Average Order Value). Using first principles, Revolve’s main product isn’t a dress; it’s the marketing expense. The influencer trip is not just a cost; it is the intangible asset that allows them to maintain a $300 price point for a dress. This experiential luxury marketing, powered by a network of 5,000+ influencers, has driven its owned-brand penetration to 35% of sales, further boosting margins.

The focus on experiential luxury marketing allows Revolve to build a digital model while using temporary pop-ups as low-CapEx market research before committing to a permanent location. Their Aspen pop-up in December 2024 converted to a full flagship in June 2025 after crushing performance metrics, and they’re replicating the playbook with a permanent store at LA’s The Grove. Focusing on brand experience, margins, and building a cash fortress creates optionality, which is a much different playbook than most apparel retailers play: heavy CapEx expansion to drive growth, which is more inflexible and likely requires leverage.

Very few companies in any industry possess both traits simultaneously. When you find one, especially one trading at a reasonable earnings multiple with a proven ability to grow, it’s worth paying attention. Revolve isn’t a “hot” stock. It doesn’t have 150% YoY growth. It is a quiet, compounding machine built on genuine structural advantages, like a pristine balance sheet and 54% margins that the market keeps overlooking.